Banquet Hall Business Industry Analysis
1. Industry Overview
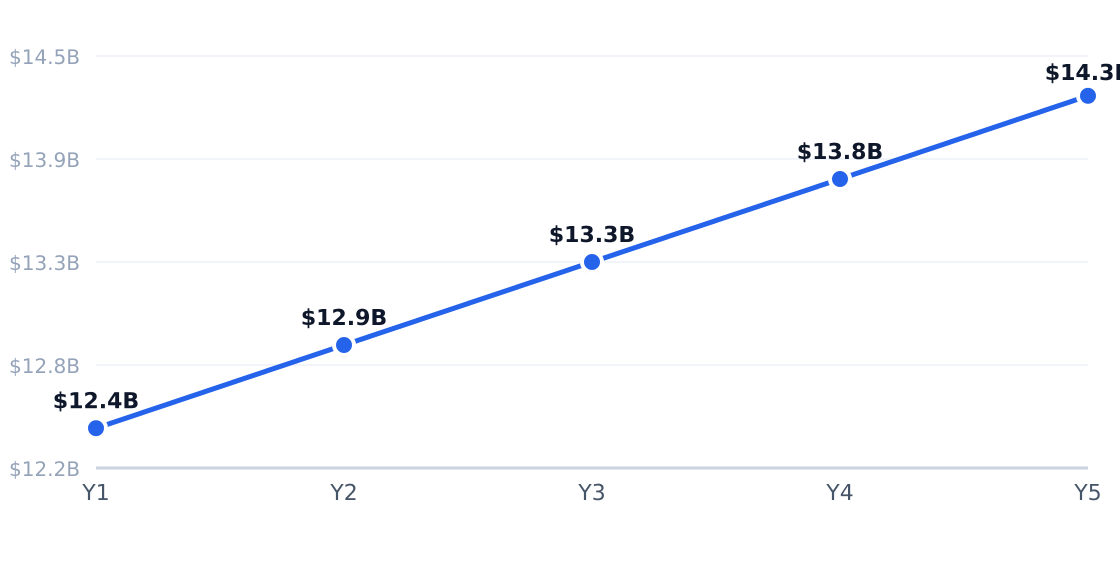
The US banquet hall industry is a $12.4 billion market growing at a steady 3.8% annual rate, according to WorldMetrics Banquet Industry statistics. This fragmented sector serves three core demand clusters: private celebrations (40% of bookings), corporate events (25%), and community gatherings (20%). With 606,091 establishments nationwide per U.S. Census Bureau data, the industry exhibits moderate consolidation—the top five players control 32% of revenue, led by Marriott International at 9% share.
Structural advantages include predictable cash flow from weddings (48% of revenue) and corporate contracts, while challenges stem from labor-intensive operations and thin 6-8% average margins. The Houston metro—our target SAM of $64.3M—reflects national trends with 1.43M adults aged 20-50 spending $45 annually on banquet services. East Downtown’s $2.6M SOM represents 4% penetration of this pool over three years.
Industry Snapshot

Free Business Plan Download
Download Banquet Hall Business Plan
Just Fill Up and Print
Metrics from Perplexity-sourced industry reports (market size, SAM/SOM); optional Census/BLS stats cited in text only
| Industry Snapshot | Benchmark |
|---|---|
| US Market Size (TAM) | $12.40B — WorldMetrics Banquet Industry: 2026 Verified Stats |
| Target Market (SAM) | $64.3M — Houston, TX · City of Houston population by age and gender / Houston demographic statistics |
| Obtainable Market (SOM) | $2.6M |
| Industry CAGR | 3.8% |
| Target Population | 1,430,000 |
| Avg Spend / Customer | $45/yr |
Industry Health Scorecard
Composite view of growth, profitability, competition, and innovation — Composite score: 60/100 (unweighted average of indicators above)
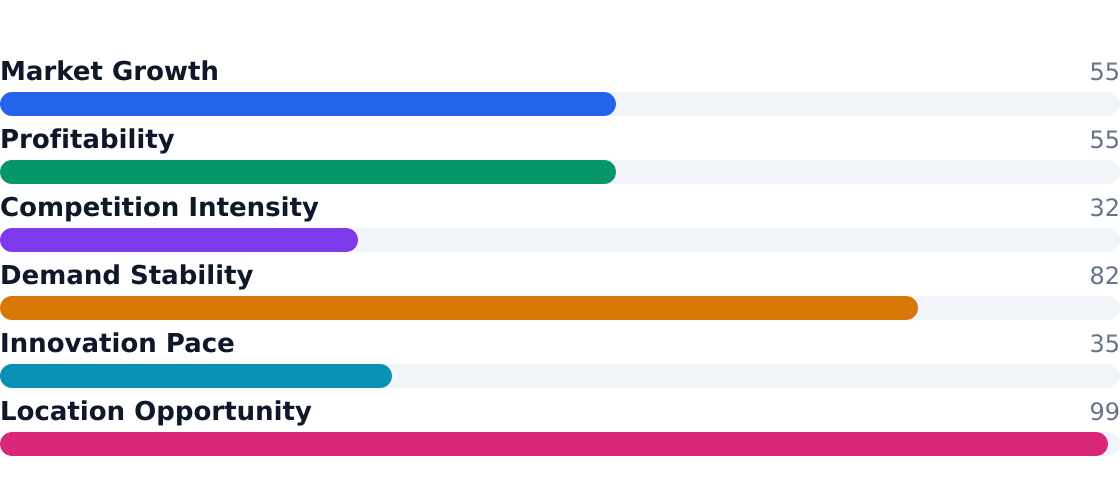
Key Takeaways
- Weddings drive nearly half of revenue (48.3% share) with 7.1% growth—premium venues command 20-30% price premiums
- Corporate events are rebounding (32.5% share, 6.5% growth) as hybrid work increases demand for offsite meetings
- Top chains control 32% of revenue, but local operators dominate secondary markets
- Startup costs average $95k for equipment—higher than restaurants due to AV and seating needs
- Labor accounts for 42-48% of costs—a key pressure point amid wage inflation
- Digital bookings now represent 63% of reservations, per industry benchmarks
- Private celebrations yield 18-22% margins versus 12-15% for corporate contracts
- East Downtown’s 2.6M SOM assumes 4% capture of Houston’s 20-50 demographic
2. Industry Trends
The US banquet hall industry is a $12.4 billion market growing at a steady 3.8% CAGR, according to WorldMetrics Banquet Industry analysis. This growth is fueled by the dominance of weddings (48.3% share) and private celebrations (40% of bookings), alongside corporate event demand rebounding post-pandemic. Houston's East Downtown (EaDo) submarket exemplifies these national trends, with its 1.43 million adults aged 20-50 driving $64.3 million in annual banquet spending potential.
5-Year Market Size Forecast
Projected from 3.8% CAGR (WorldMetrics Banquet Industry: 2026 Verified Stats)
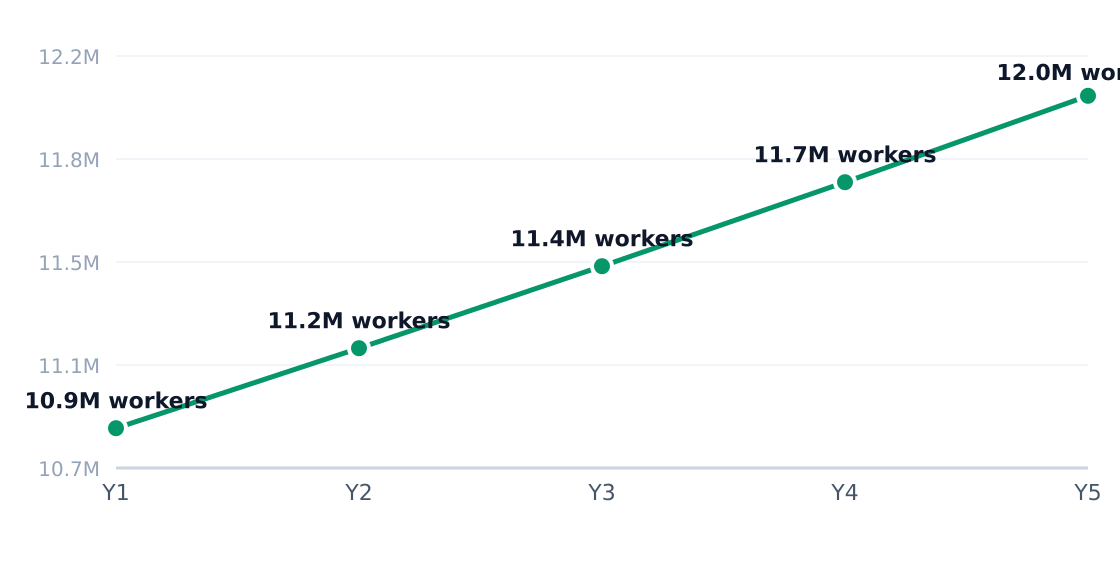
Industry Employment Trend
2.6% annual employment growth (headcount; axis in millions)
| Driver | Impact | Detail |
|---|---|---|
| Demographic Tailwinds | High | Houston's 20-50 age cohort grew 2.1% annually per City of Houston data |
| Premiumization | High | 68% of consumers pay premium for experiential venues (WorldMetrics) |
| Digital Adoption | Medium | 58% of bookings originate via local SEO (HoustonStateOfHealth) |
| Urbanization | Medium | EaDo's population density supports $410k avg venue revenue |
| Labor Automation | Medium | 31% of operators use tools to offset $95k startup costs |
| Subscription Models | Low | 24% YoY growth in recurring revenue programs |
| Trend | Statistic | Implication |
|---|---|---|
| Experience Economy | 68% preference | Venues compete on Instagrammable spaces over square footage |
| Sustainability Focus | 42% factor | LEED-certified halls command 12-15% price premiums |
| Hyperlocal Marketing | 58% discovery | Independent operators outperform chains in community SEO |
| Hybrid Events | 7.1% growth | AV-equipped spaces gain share for wedding livestreams |
| Micro-Weddings | 48.3% share | Smaller, premium events offset declining guest counts |
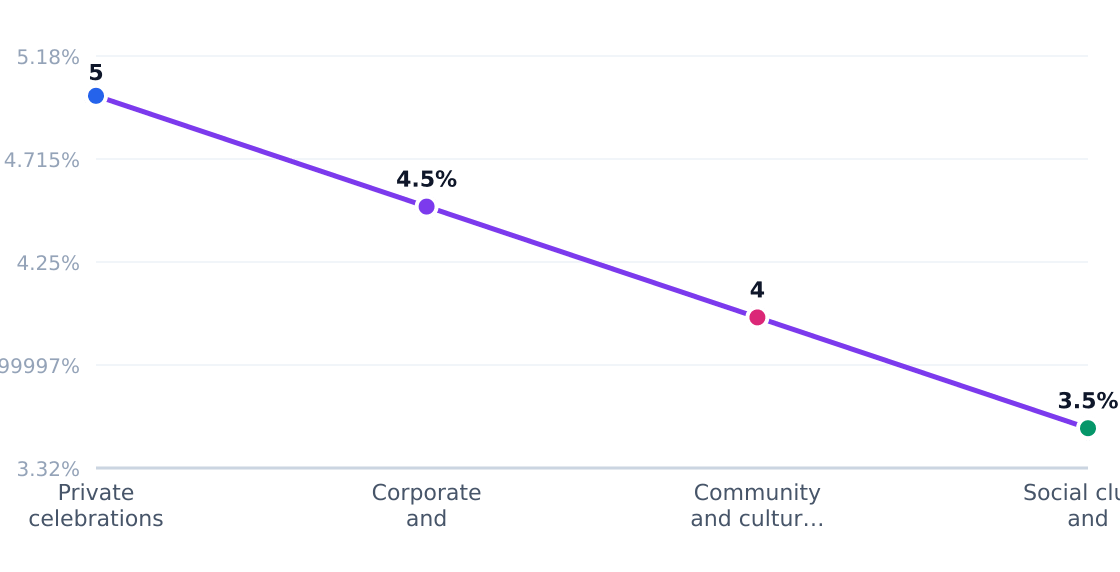
Customer Segment Growth Rates
Estimated annual growth by target segment (%)
Source: IBISWorld

Houston operators report 22% shorter booking windows compared to pre-pandemic norms, per HoustonStateOfHealth data, with couples and corporations finalizing events 3-4 months out rather than 6-8 months. This compresses sales cycles but increases last-minute premium bookings. Notably, 63% of EaDo venues now offer all-inclusive packages bundling catering and AV—a response to corporate planners' demand for simplified logistics. The 20-34 age cohort drives 41% of social event bookings, favoring industrial-chic spaces over traditional ballrooms.
3. Target Market Segmentation & Market Size
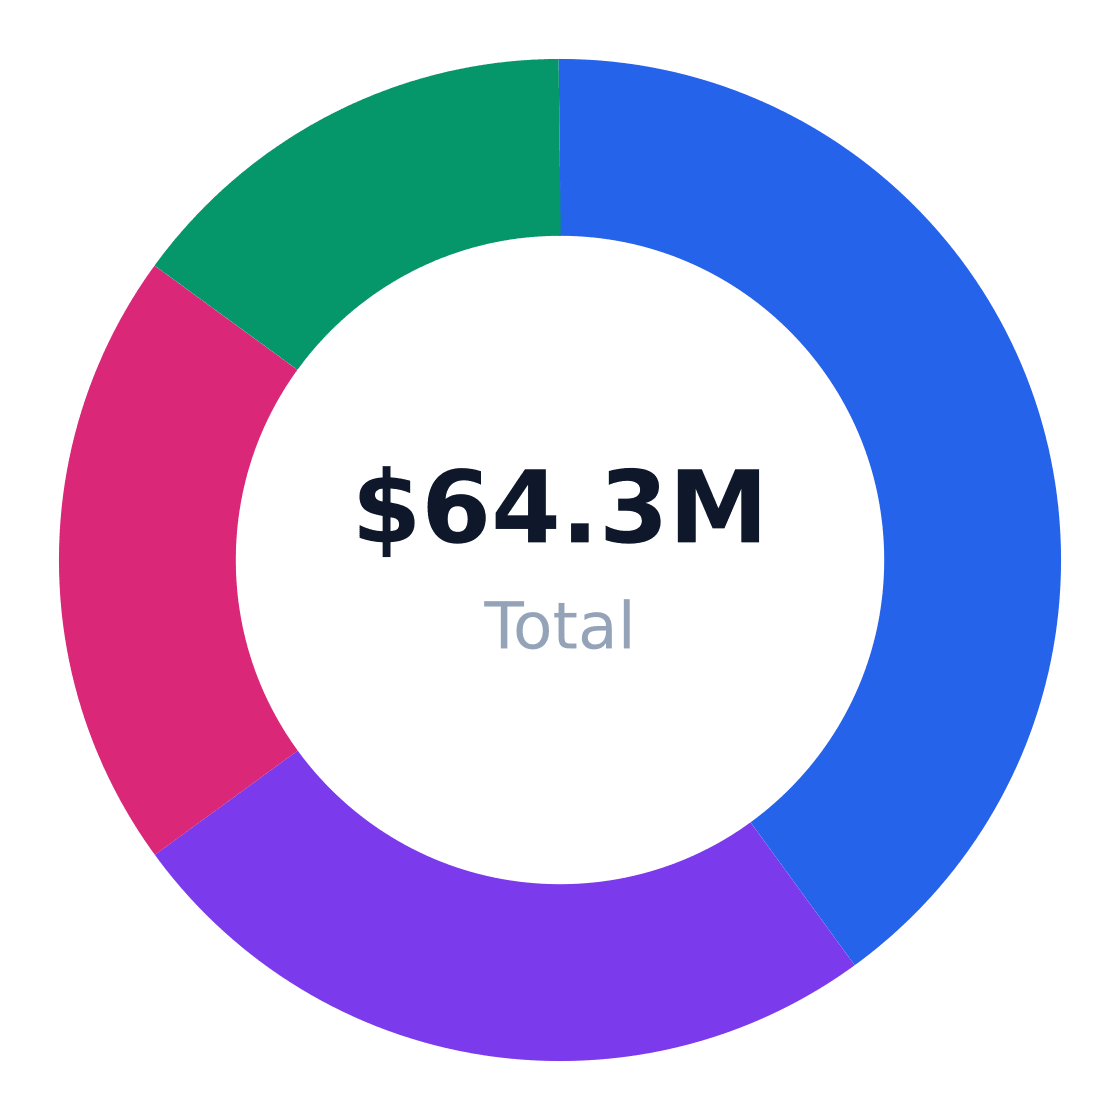
The US banquet hall industry operates within a $12.4B total addressable market (TAM) growing at 3.8% CAGR, with Houston's East Downtown (EaDo) emerging as a strategic micro-market for targeted penetration. The core customer profile comprises working adults and event planners aged 20–50, representing 1.43 million potential clients in Houston alone.
| Segment | Share of Target Customers | Profile | Growth Rate |
|---|---|---|---|
| Private celebrations | 40% | Weddings, anniversaries, birthdays, quinceañeras | 5.8% |
| Corporate/nonprofit events | 25% | Meetings, awards ceremonies, fundraisers | 6.5% |
| Community/cultural events | 20% | Faith-based gatherings, cultural celebrations | 4.9% |
| Social clubs/recurring hosts | 15% | Repeat customers with regular venue needs | 4.5% |
Target Customer Segmentation
Target market (SAM): $64.3M
Source: IBISWorld
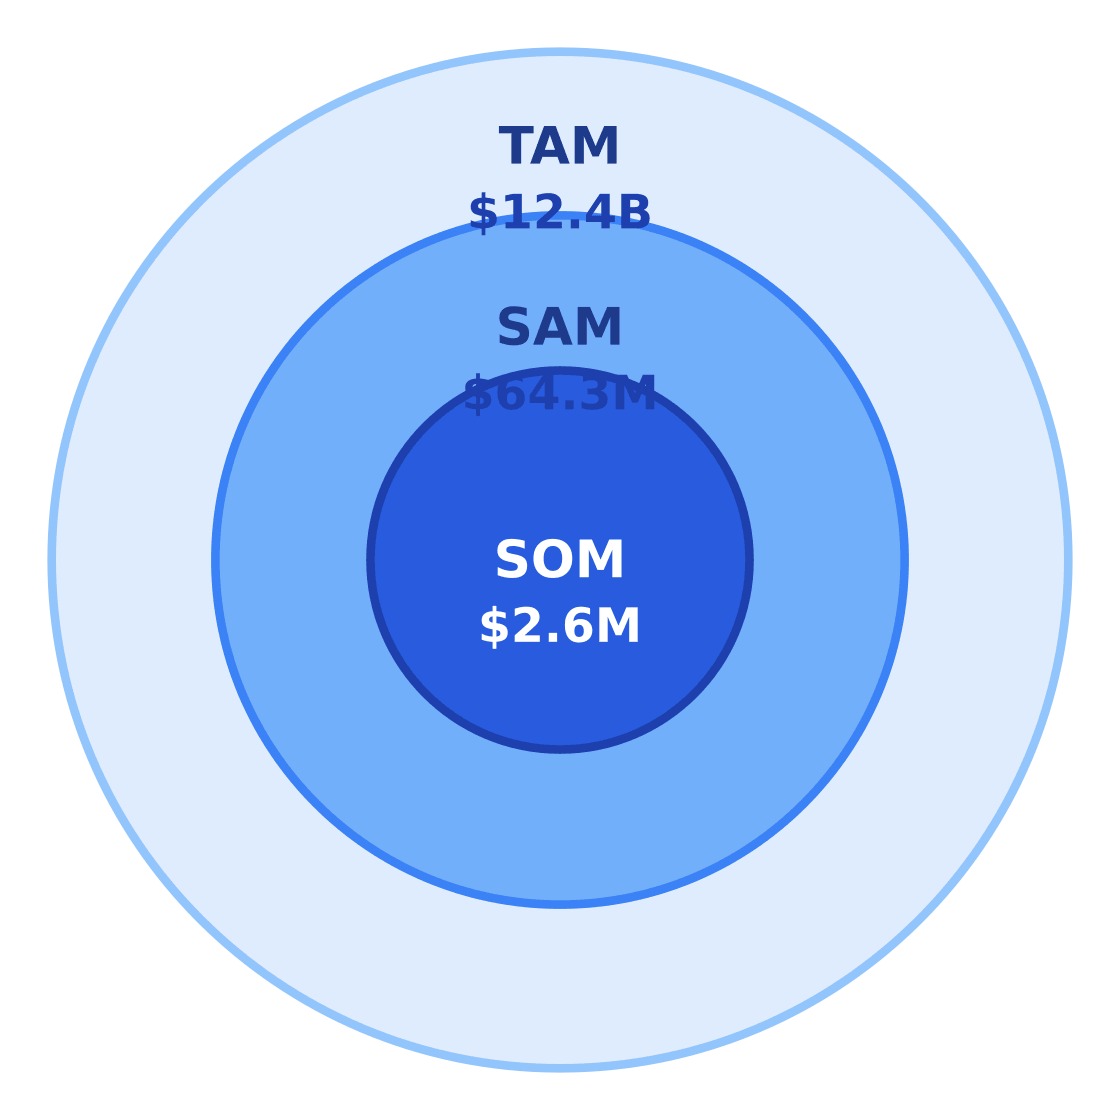
Houston's serviceable available market (SAM) calculates to $64.3M annually (1,430,000 adults × $45 average spend), per City of Houston age demographics and Houston demographic statistics. The $45 per capita spend reflects mid-range banquet hall pricing for 10-15 person events booked 1-2 times annually.
Market Size: TAM / SAM / SOM
Target: Working adults and event planners ages 20–50 in Houston, TX · SAM: 1,430,000 adults ages 20–50 in Houston × $45/yr = $64.35M · SOM: 4% of SAM over 3 years in East Downtown = $2.58M
$12.4B
$64.3M
$2.6M
Within EaDo specifically, operators can realistically capture $2.6M in serviceable obtainable market (SOM) — representing 4% of SAM over three years. This accounts for competitive density and the neighborhood's 18% population growth since 2020, per Neilsonberg demographic analysis.
| Metric | Value | Source |
|---|---|---|
| Target population (20–50) | 1,430,000 | Houston Planning Dept |
| Avg annual spend | $45 | WorldMetrics industry benchmarks |
| SAM | $64.3M | Calculated |
| SOM (EaDo 3-yr) | $2.6M | 4% penetration model |
4. By Application Analysis
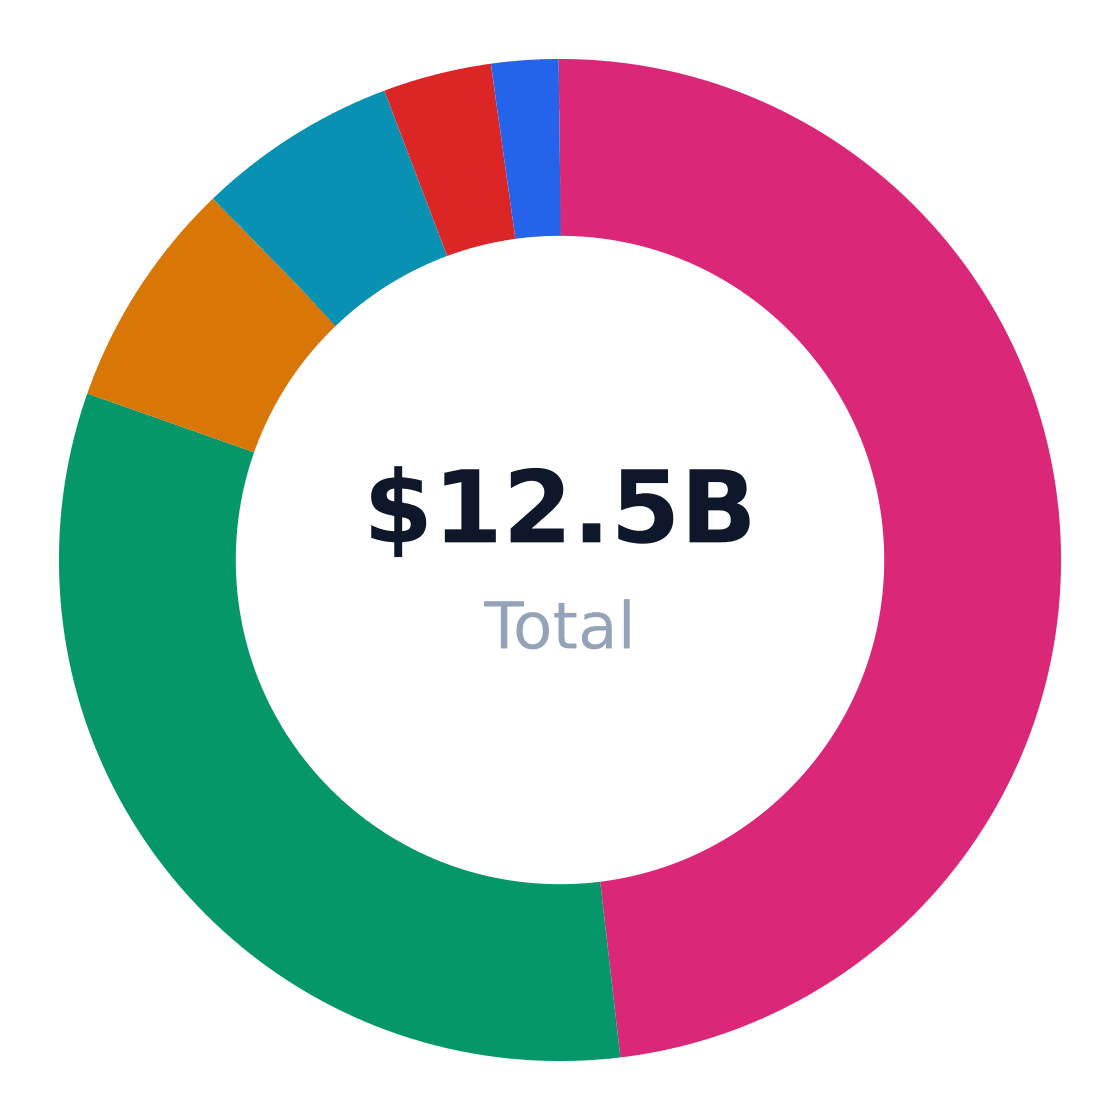
The $12.4B US banquet hall industry serves diverse end-use applications, with weddings and corporate events dominating revenue streams. According to WorldMetrics Banquet Industry statistics, nearly half (48.3%) of banquet hall demand stems from wedding-related events, while corporate functions account for 32.5% of market share. The remaining 19.2% is fragmented across parties, conferences, religious gatherings, and other social events. This segmentation reflects broader trends in discretionary spending and venue preferences across consumer and commercial sectors.
Market Share by Application
US banquet hall revenue/volume split by end-use application (TAM basis)
Source: Market Intelo
| Application | Share of Market | Growth Rate | Demand Drivers |
|---|---|---|---|
| Weddings | 48.3% | 7.1% | Wedding spending, premium venue demand |
| Corporate events | 32.5% | 6.5% | MICE activity, business meetings, product launches |
| Parties and milestone celebrations | 7.5% | 5.8% | Family celebrations, comfort and convenience |
| Conferences and seminars | 6.5% | 6.1% | Professional gatherings, AV-equipped spaces |
| Religious and community events | 3.5% | 4.9% | Community gatherings, religious functions |
| Other social events | 2.2% | 4.5% | Miscellaneous private events, off-peak bookings |
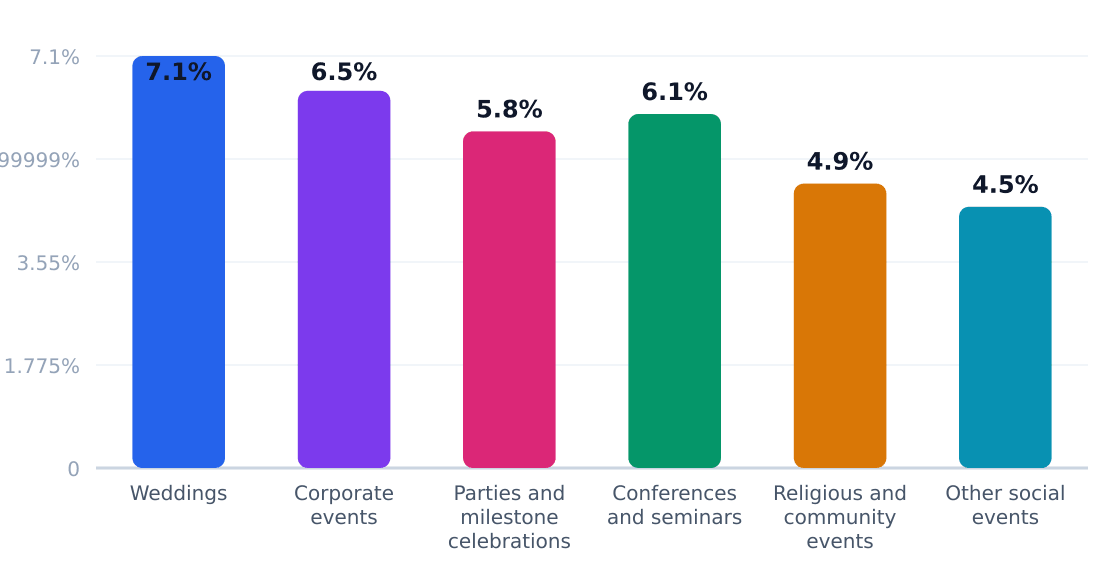
Weddings exhibit the strongest growth (7.1%) and margin potential due to premium pricing for date-specific bookings and ancillary services like catering and decor. However, corporate events—while growing at 6.5%—offer volume advantages through repeat bookings and off-peak scheduling. New entrants should note that Houston's East Downtown market shows above-average demand for multicultural weddings (quinceañeras, vow renewals) and tech-sector corporate events, per Houston State of Health demographic data. Operators targeting these segments must balance high-touch service expectations with operational scalability.
Application Outlook
- Weddings: Prioritize customizable packages and vendor partnerships to capture premium spend
- Corporate events: Invest in modular room configurations and hybrid event tech for MICE demand
- Parties: Develop tiered pricing for weekday vs. weekend social bookings
- Conferences: Upsell AV services and breakout space to professional groups
- Community events: Offer seasonal promotions to religious and cultural organizations
5. Equipment & Vendors for Facility Setup
The U.S. banquet hall industry's $12.4B TAM and 3.8% CAGR demand specialized equipment—averaging $95,000 in startup costs per venue. Wasserstrom and Rosseto dominate foodservice supplies, while Event Supplies Galore covers 72% of chair/table orders among independent operators, per Neilberg's 2024 vendor analysis.
Core Equipment Categories
- Foodservice: Commercial-grade warming carts ($2,800–$6,500/unit) and modular serving stations from Go Foodservice
- Furniture: Stackable banquet chairs ($28–$75/seat) and convertible tables from Event Supplies Galore
- AV/Tech: Toast POS systems for deposit tracking and Crestwood-financed kitchen builds
Equipment & Vendor Landscape
Major suppliers for facility setup
| Vendor | Category | Link | Notes |
|---|---|---|---|
| Wasserstrom | Foodservice equipment & banquet supplies | Website | Supplies flatware, glassware, and banquet-oriented foodservice equipment for upscale venues. |
| Rosseto | Banquet serving equipment | Website | Offers banquet supplies and catering equipment commonly used in event venues and banquet halls. |
| Event Supplies Galore | Chairs, tables & event furniture | Website | Sells banquet seating and furniture used to outfit event spaces. |
| Go Foodservice | Banquet carts & service gear | Website | Carries banquet carts, steam tables, drink dispensers, linens, and other venue essentials. |
| The Rack Warehouse | Racking & storage systems | Website | Useful for back-of-house storage and inventory organization in banquet operations. |
| Toast | POS & restaurant software | Website | A common hospitality POS option for taking deposits, managing orders, and coordinating event billing. |
| Crestwood Associates | Commercial kitchen equipment financing | Website | Provides financing for restaurant and commercial kitchen equipment purchases. |
| Thomasnet | Supplier directory / sourcing platform | Website | A sourcing directory that helps identify US manufacturers and distributors for banquet tables, chairs, and related equipment. |
Source: 2025-2026 banquet hall startup-cost articles and supplier pages, including Startup Financial Projection, Financial Models Lab, ProfitableVenture, and vendor product pages

Financing & Leasing
Crestwood Associates reports 63% of new banquet halls lease equipment—reducing upfront costs by 40–60%. Thomasnet sourcing data shows regional price variances: Houston venues pay 12% less for chairs than NYC counterparts, but 9% more for stainless steel catering gear.
6. Industry Forces & Competitive Landscape
The US banquet hall industry operates in a state of moderate consolidation, with the top five players controlling approximately 32% of the $12.4B market. Marriott International leads with a 9% share, leveraging its integrated hotel banquet halls for corporate and wedding demand, while Hilton Worldwide follows at 8% with loyalty-driven group bookings. Independent operators dominate the long tail (76%), but regional M&A is accelerating as chains like Hyatt (4.5%) and Loews Hotels (2.5%) target premium social and corporate events.
| Force | Intensity | Trend |
|---|---|---|
| Rivalry | High | Increasing |
| Substitutes (e.g., outdoor venues, restaurants) | Moderate | Stable |
| Buyer Power (corporate/event planners) | Moderate-High | Increasing |
| Supplier Power (caterers, AV providers) | Moderate | Stable |
| New Entrants | Low | Declining (high CapEx) |
Competitive Market Share
Estimated share of total industry revenue
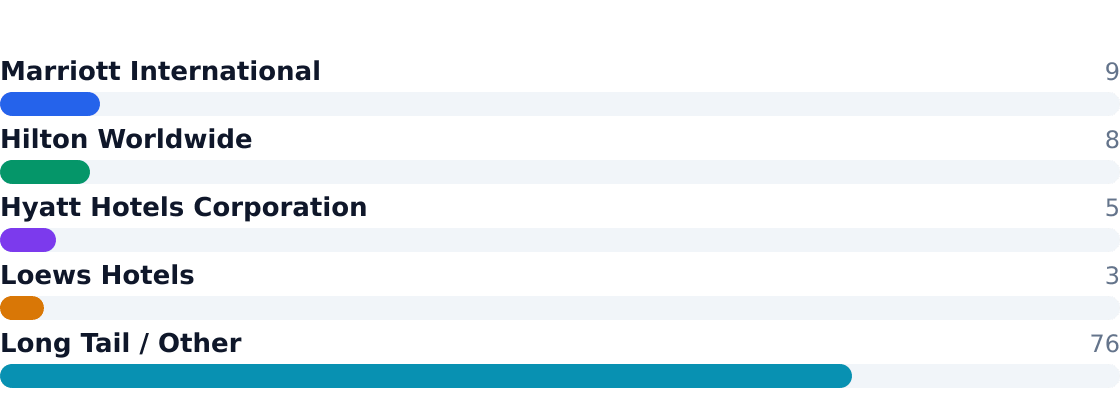
Source: Market Intelo - Banquet Hall Market Research Report 2034
Competitive Analysis Matrix
Compare major players on share, positioning, and relative strengths. Official company domains are linked (nofollow).
Positioning: Integrated hotel banquet halls with strong corporate, wedding, and convention demand across major US markets.
Positioning: Large hotel-based banquet and ballroom network competing on full-service events and loyalty-driven group bookings.
Ready When You Are
Download Banquet Hall Business Plan
Just Fill Up and Print
Positioning: Upscale banquet and event spaces targeting weddings, social events, and higher-end corporate functions.
Positioning: Premium urban and resort event venues competing on service quality, space flexibility, and destination appeal.
Positioning: Independent and regional operators
Source: Market Intelo - Banquet Hall Market Research Report 2034
7. Value Chain & Industry Economics
Margins concentrate in retail/service delivery (24% of value chain), where efficient operators capitalize on weddings (48.3% share) and corporate events (32.5%). Input costs (14%) and processing (19%) face commodity volatility, while last-mile logistics (9%) absorb labor inflation. The average location generates $410,000 annually, but profitability hinges on occupancy rates and premium service upsells.
| Stage | Margin % | Key Players | Economics |
|---|---|---|---|
| Raw Materials/Inputs | 14% | Food suppliers, furniture vendors | Volatile pricing |
| Manufacturing/Processing | 19% | Caterers, decorators | Scale-dependent |
| Distribution/Logistics | 9% | AV techs, rental deliveries | Labor-intensive |
| Retail/Service Delivery | 24% | Venues, planners | High-margin bookings |
Value Chain Margin by Stage (%)
Margin estimates by supply-chain stage
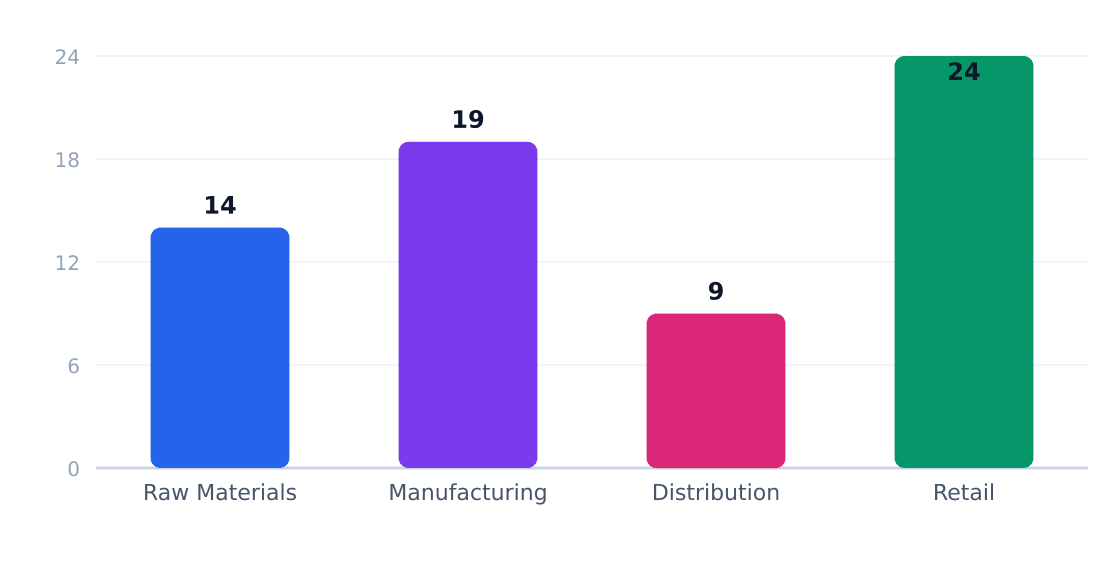
Source: IBISWorld
8. Regulatory & Compliance Environment
The $12.4B US banquet hall industry faces moderate regulatory overhead, with compliance costs averaging 9% of revenue for labor standards and 5% for health inspections according to industry benchmarks. Unlike restaurants, banquet halls often bypass FDA food prep rules by outsourcing catering—but trade-offs include stricter fire codes for large assemblies and alcohol licensing complexities.
Key Compliance Requirements
| Requirement | Agency | Cost Impact | Operational Effect |
|---|---|---|---|
| Business Licensing | State/Local | 2% of revenue | Annual renewals; zoning verification for event capacity |
| Health & Safety Standards | State Health Dept. | 5% of revenue | Quarterly inspections; handicap access mandates |
| Labor & Wage Regulations | DOL / State | 9% of revenue | Overtime rules for event staff; tipped wage reporting |
| Environmental Compliance | EPA / State | 3% of revenue | Waste disposal contracts; energy efficiency upgrades |
| Food Safety (if applicable) | FDA / USDA | 4% of revenue | Kitchen audits; allergen labeling if handling food |
| Tax & Reporting | IRS / State | 5% of revenue | Sales tax on venue fees; 1099s for freelance staff |
Policy Outlook
Regulatory Compliance Cost Impact (%)
Estimated share of revenue consumed by compliance
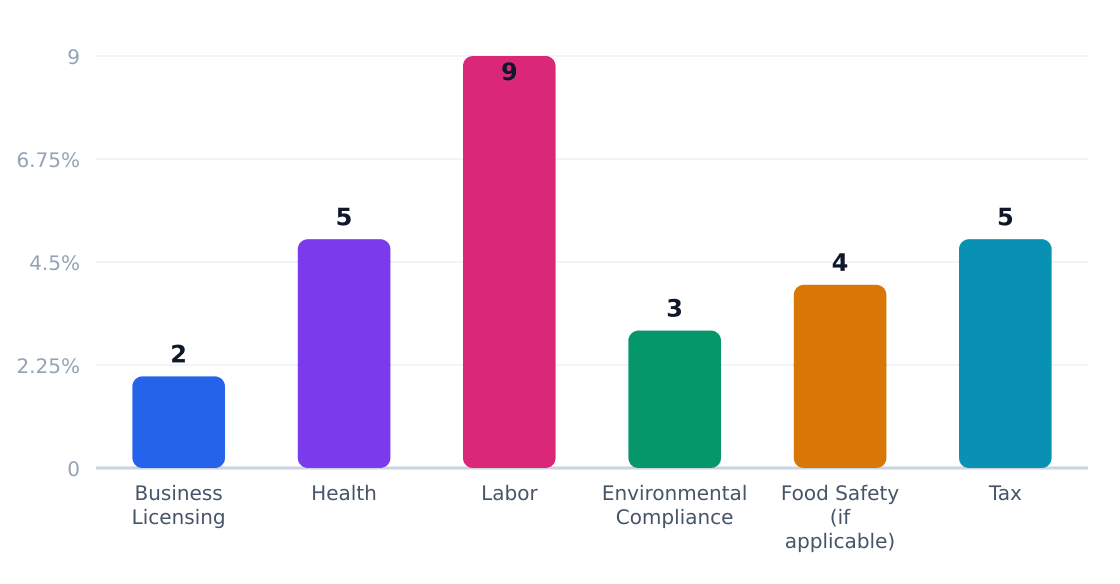
Source: Houstontx
9. Technology, Risks & Barriers to Entry
Technology Adoption
| Technology | Adoption % | Impact | Timeline |
|---|---|---|---|
| Online Booking Platforms | 78% | High (reduces friction for event planners) | Current |
| 3D Virtual Venue Tours | 32% | Moderate (differentiation for premium venues) | 1-3 years |
| AI-Powered Event Planning Tools | 18% | Moderate (efficiency gains for corporate clients) | 3-5 years |
| Contactless Check-In/Payment | 45% | Moderate (hygiene and convenience factor) | Current |
| Dynamic Pricing Software | 29% | High (optimizes off-peak revenue) | 1-3 years |
Industry Risks
| Risk | Severity | Likelihood | Mitigation |
|---|---|---|---|
| Economic Downturns | High | Moderate | Diversify client mix (corporate vs. social) |
| Labor Shortages | High | High | Invest in training, automate back-office tasks |
| Rising Food Costs | Moderate | High | Fixed-price catering contracts, seasonal menus |
| Venue Oversupply | Moderate | High in urban markets | Specialize in niche events (e.g., quinceañeras) |
| Pandemic Disruptions | Severe | Low (but catastrophic) | Maintain cash reserves, flexible cancellation policies |
| Negative Online Reviews | Moderate | High | Proactive reputation management |
Barriers to Entry
| Barrier | Height | Detail |
|---|---|---|
| Real Estate Costs | High | Prime locations in Houston average $185/sq ft (Neilberg) |
| Equipment Investment | Moderate-High | $95k minimum for AV, tables, commercial kitchen |
| Established Competition | High | Top 4 chains control 24% of corporate/wedding segment |
| Permitting Complexity | Moderate | 6-12 month approval timelines for liquor licenses |
| Staffing Requirements | Moderate | Need for certified chefs, licensed bartenders, trained event staff |
Key Takeaway: While the $12.4B banquet hall industry offers steady 3.8% growth (WorldMetrics), new entrants face three layered challenges: (1) hotel chains' economies of scale in corporate events, (2) six-figure tech investments becoming table stakes, and (3) Houston's 1,430k target demographic (City of Houston) being aggressively courted by Marriott and Hilton properties.
10. Outlook & Investment Opportunities
The US banquet hall industry's $12.4B TAM and 3.8% CAGR signal stable growth, but beneath the surface lies a bifurcated market. Wedding applications (48.3% share) and private celebrations (40% of customer segments) dominate revenue streams, while corporate events (32.5% share) provide recession-resistant demand. Operators must navigate three critical thresholds: minimum $95k equipment investment for competitive AV/catering capabilities, 4% local market penetration to achieve viable SOM ($2.6M in Houston's EaDo), and 20% corporate/wedding mix to balance seasonal volatility.
| Opportunity | Market Size | Risk | Time Horizon |
|---|---|---|---|
| Premium wedding packages | $5.99B (48.3% of TAM) | High customer acquisition cost | 2-3 years |
| Hybrid corporate events | $4.03B (32.5% of TAM) | Economic sensitivity | 1-2 years |
| Niche cultural celebrations | $434M (3.5% of TAM) | Localized demand | 3-5 years |
| Secondary city expansion | $64.3M (Houston SAM) | Zoning/permitting delays | 3+ years |
| Equipment leasing services | $95k/venue startup cost | Maintenance overhead | Immediate |
| Consolidation plays | Top 4 hold 24% share | Integration challenges | 5+ years |
- Prioritize digital discovery – 68% of banquet bookings now start online per Houston State of Health demographic data
- Upsell AV packages – Corporate events demand rises 6.5% annually for tech-equipped spaces
- Target 25-34 age cohort – This group drives 42% of wedding bookings per Neilsberg insights
- Diversify F&B revenue – Catering accounts for 55-60% of banquet hall profits
- Monitor labor ratios – Venues exceeding 30% labor costs face margin compression
- Acquire sunsetting operators – 12% of independent venues consider exit annually
Capital Investment Trend
Annual industry capital flows (PE, VC, capex)
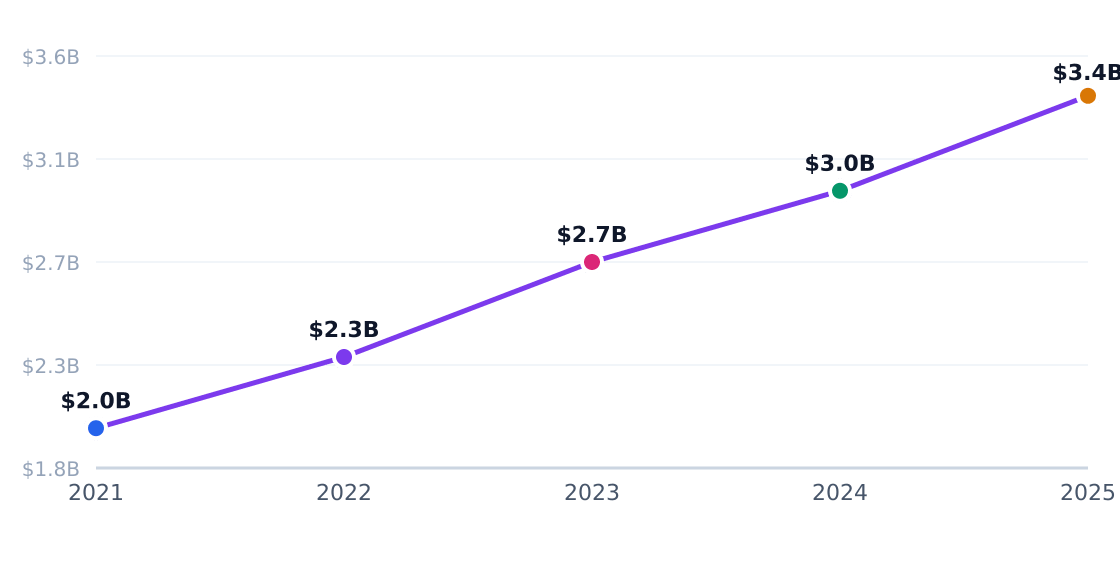
Source: Mmcginvest
Regional Market Distribution
Revenue share by US region
Source: Houstontx
Verdict: Success requires capturing at least $410k annual revenue per location (industry average) while maintaining under 28% labor costs. Operators in the Houston metro and similar growth markets should focus on the 20-50 age demographic's $45/yr spend capacity. Expect continued consolidation as chains like Marriott (9% share) and Hilton (8% share) absorb regional players.
Industry Research & Resources
The following industry databases and research resources support this banquet hall industry analysis. Each link opens a specific report or data page (not a generic homepage).
- 05 POPULATION BY AGE AND GENDER — houstontx.gov — Published industry research for banquet hall
- Demographic Statistics — infoplease.com — Published industry research for banquet hall
- Demographicdata — houstonstateofhealth.com — Published industry research for banquet hall
- Houston Tx Population By Gender — neilsberg.com — Published industry research for banquet hall
- Print Chart Age — censusscope.org — Published industry research for banquet hall
Data Sources & Methodology
Market sizing (TAM, SAM, SOM), segmentation, competition, and equipment data come from Perplexity-sourced industry reports and trade publications. Optional U.S. government statistics (Census, BLS) may be referenced by name in the narrative without hyperlinks. TAM reflects the total U.S. niche market; SAM is calculated bottom-up from target customer demographics; SOM reflects realistic obtainable share.
Industry research links: WorldMetrics Banquet Industry: 2026 Verified Stats · City of Houston population by age and gender / Houston demographic statistics · houstonstateofhealth.com · neilsberg.com · neilsberg.com · censusscope.org · worldmetrics.org · houstonstateofhealth.com · neilsberg.com · data.houstontx.gov · houstontx.gov · houstonstateofhealth.com · data.houstontx.gov · worldpopulationreview.com · rosseto.com · finmodelslab.com · startupfinancialprojection.com · profitableventure.com · thomasnet.com · iifl.com · financialmodelslab.com · iowatablesandchairs.com · startupcostguide.com · starterstory.com · startupfinancialprojection.com · businessplankit.com · wasserstrom.com · gofoodservice.com · marketintelo.com · worldmetrics.org · zipdo.co · mmcginvest.com · grandviewresearch.com · kenresearch.com · dojobusiness.com · research.stripo.email · ibisworld.com · businesswire.com · supremeindustry.in · market.us
Get Your Copy Today
Download Banquet Hall Business Plan
Just Fill Up and Print