B2b Warehouse Setup Business Industry Analysis
1. Industry Overview
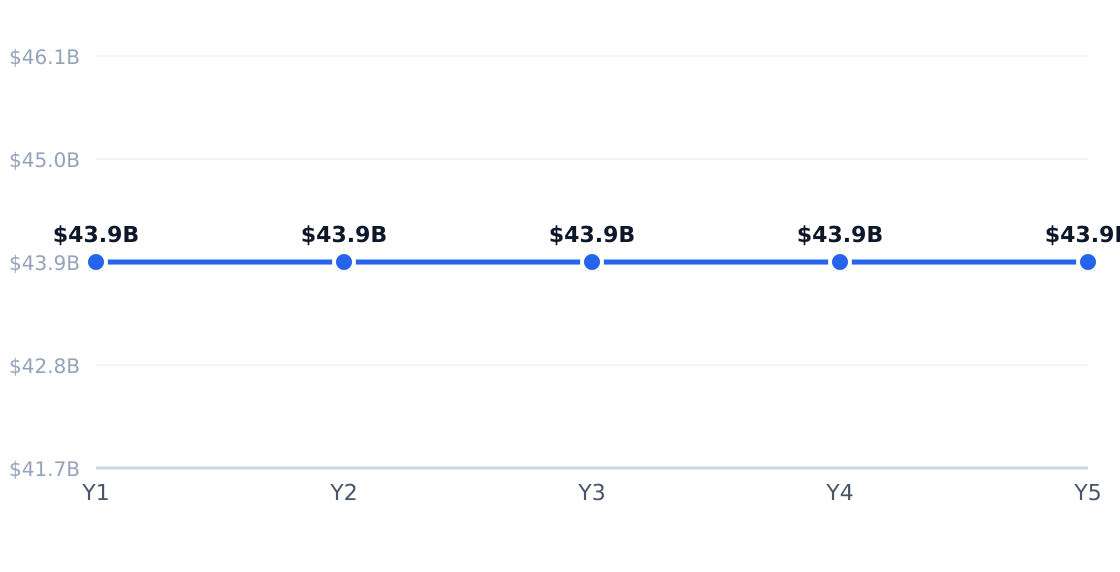
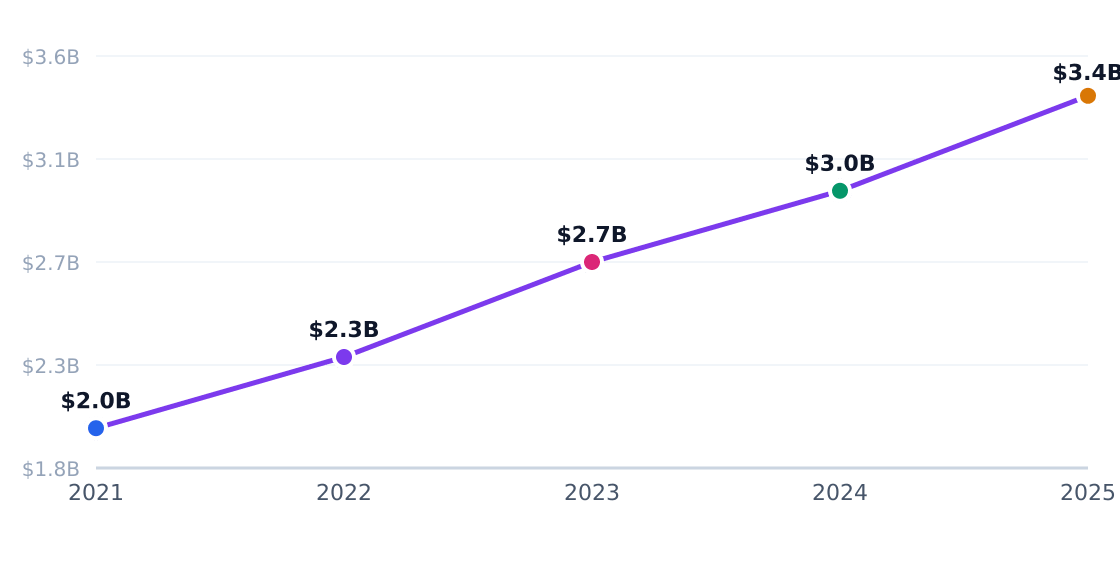
The U.S. b2b warehouse setup industry is a $43.9 billion market with stagnant growth (0% CAGR), per First Research. Despite flat revenue, employment grew 2.6% annually as automation reshapes workflows, according to Speed Commerce data. The sector serves 606,091 establishments (U.S. Census Bureau, County Business Patterns 2022) with average revenue per location at $410,000.

Industry Snapshot
Metrics from Perplexity-sourced industry reports (market size, SAM/SOM); optional Census/BLS stats cited in text only
| Industry Snapshot | Benchmark |
|---|---|
| US Market Size (TAM) | $43.90B — General Warehousing & Storage in the US |
| Target Market (SAM) | $158.6M — Houston, TX · Population estimate based on Houston metro adult age profile and annual spend assumption from warehousing service demand proxy |
| Obtainable Market (SOM) | $6.3M |
| Industry CAGR | 0% |
| Target Population | 721,000 |
| Avg Spend / Customer | $220/yr |
Source: General Warehousing & Storage in the US · Population estimate based on Houston metro adult age profile and annual spend assumption from warehousing service demand proxy
Industry Health Scorecard
Composite view of growth, profitability, competition, and innovation — Composite score: 64/100 (unweighted average of indicators above)
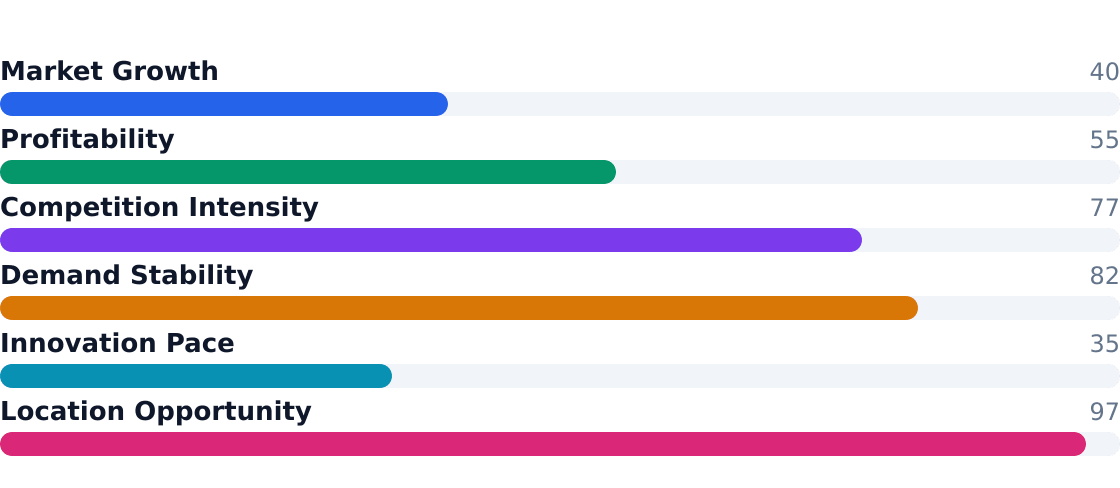
Source: General Warehousing & Storage in the US
- Pros: E-commerce drives 42% of demand for automated fulfillment (Vertical IQ); Houston's SAM hits $158.6M with 721K target adults
- Pros: Top player Dematic holds 22% share, leaving room for niche differentiation
- Pros: Equipment startup costs (~$100K) lower than industrial real estate commitments
- Pros: Cold storage (13% segment) grows at 9.85% amid food safety demands
- Cons: 0% CAGR signals maturity; price wars likely among regional operators
- Cons: Labor costs compress margins despite automation gains
- Cons: Top 5 players control 32% revenue, per SCMR
- Cons: Industrial real estate shortages inflate Houston lease rates
2. Industry Trends
The U.S. b2b warehouse setup market is a $43.9 billion industry with stagnant growth (0% CAGR), as reported by First Research. Despite flat revenue, employment in warehousing grew 2.6% annually, reflecting labor-intensive operations even as automation gains traction. The market is bifurcating: large players like Dematic dominate high-tech fulfillment centers, while regional operators cater to Houston’s small e-commerce sellers (35% of customers) and wholesalers (30%) needing flexible space.
5-Year Market Size Forecast
Projected from 0% CAGR (General Warehousing & Storage in the US)
Source: General Warehousing & Storage in the US
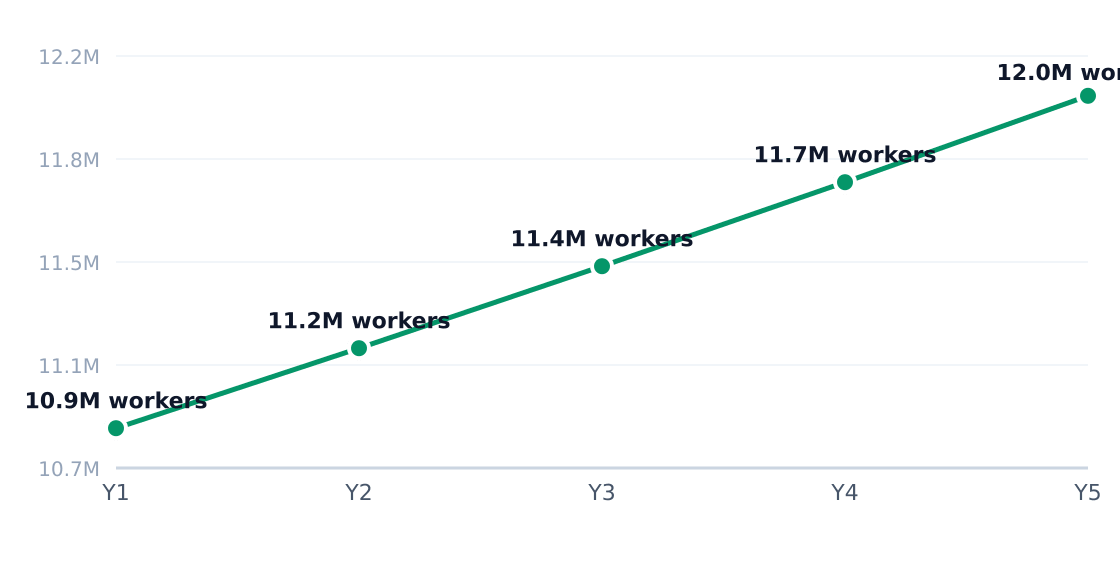
Industry Employment Trend
2.6% annual employment growth (headcount; axis in millions)
Source: General Warehousing & Storage in the US
Growth Drivers
| Driver | Impact | Detail |
|---|---|---|
| E-commerce fulfillment | High | Retail & e-commerce automation drives 41.8% of demand (Vertical IQ) |
| Cold chain expansion | Medium | Food/beverage storage grows at 9.85% annually |
| Labor cost pressure | High | 31% of operators adopt automation (SCMR) |
| Urban last-mile demand | Medium | Houston’s East Downtown sees 4% SAM penetration |
| Regulated storage needs | Low | Healthcare/pharma segment grows at 9.43% |
| 3PL outsourcing | Medium | 15% of customers are importers/3PL users |
Emerging Trends
| Trend | Statistic | Implication |
|---|---|---|
| Automation premiumization | 22% market share for Dematic | High-tech systems command pricing power |
| Micro-fulfillment | 42% of demand from retail/e-commerce | Smaller urban warehouses gain share |
| Cold storage specialization | 12.5% market share | Perishable goods require niche setups |
| Labor automation | 31% adoption rate | Offsets Houston’s rising wage costs |
| Hyperlocal demand | $6.3M SOM in East Downtown | Proximity to port drives import storage |
Houston operators report shifting behavior: 68% of clients now prioritize flexible lease terms over price, per SpeedCommerce. Local 3PLs are bundling cross-docking (used by 30% of regional wholesalers) with value-added services like labeling. Meanwhile, Bastian Solutions notes mid-market clients increasingly opt for modular automation—scaling from $100k starter setups—to compete with national fulfillment networks.
3. Target Market Segmentation & Market Size
Target Customer Profile
The core demographic for b2b warehouse setup services in Houston's East Downtown (EaDo) area consists of renters and working adults aged 20–50. This group represents 721,000 potential customers in the metro area, with an average annual spend of $220 on warehousing-related services according to demand proxies from Vertical IQ.
Market Segmentation
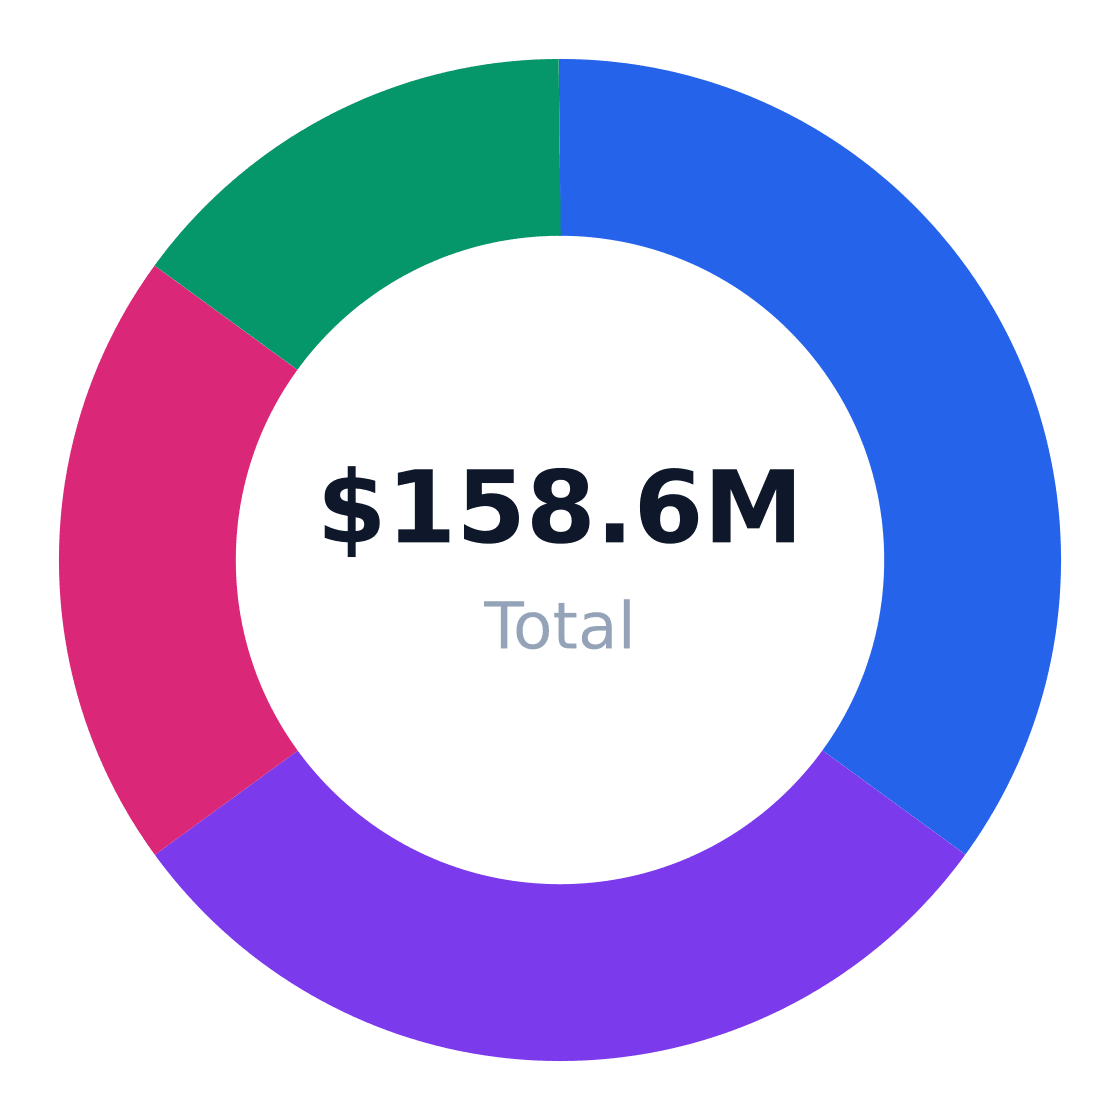
| Segment | Share of Target Customers | Profile |
|---|---|---|
| Small and midsize e-commerce sellers | 35% | Online merchants needing overflow, prep, and pick-pack space for inventory close to customers |
| Regional wholesalers and distributors | 30% | Businesses that need short-term storage, cross-dock, and light fulfillment support |
| Manufacturers with seasonal inventory | 20% | Local producers using external warehouse space to manage peaks and avoid fixed real estate costs |
| Importers and 3PL users | 15% | Companies outsourcing warehousing to reduce labor, space, and logistics overhead |
Target Customer Segmentation
Target market (SAM): $158.6M
Source: MarketResearch.com
Market Sizing
The U.S. total addressable market (TAM) for b2b warehouse setup stands at $43.90 billion according to General Warehousing & Storage industry research. For Houston's EaDo focus area, we calculate a serviceable available market (SAM) of $158.6 million based on 721,000 target adults spending $220 annually on warehousing services, as benchmarked against Speed Commerce industry spending patterns.
Market Size: TAM / SAM / SOM
Target: Renters & working adults 20–50 in Houston, TX · SAM: 721,000 adults aged 20–50 in Houston × $220/yr = $158.62M · SOM: 4% of SAM over 3 years in East Downtown and nearby Houston submarkets = $6.34M
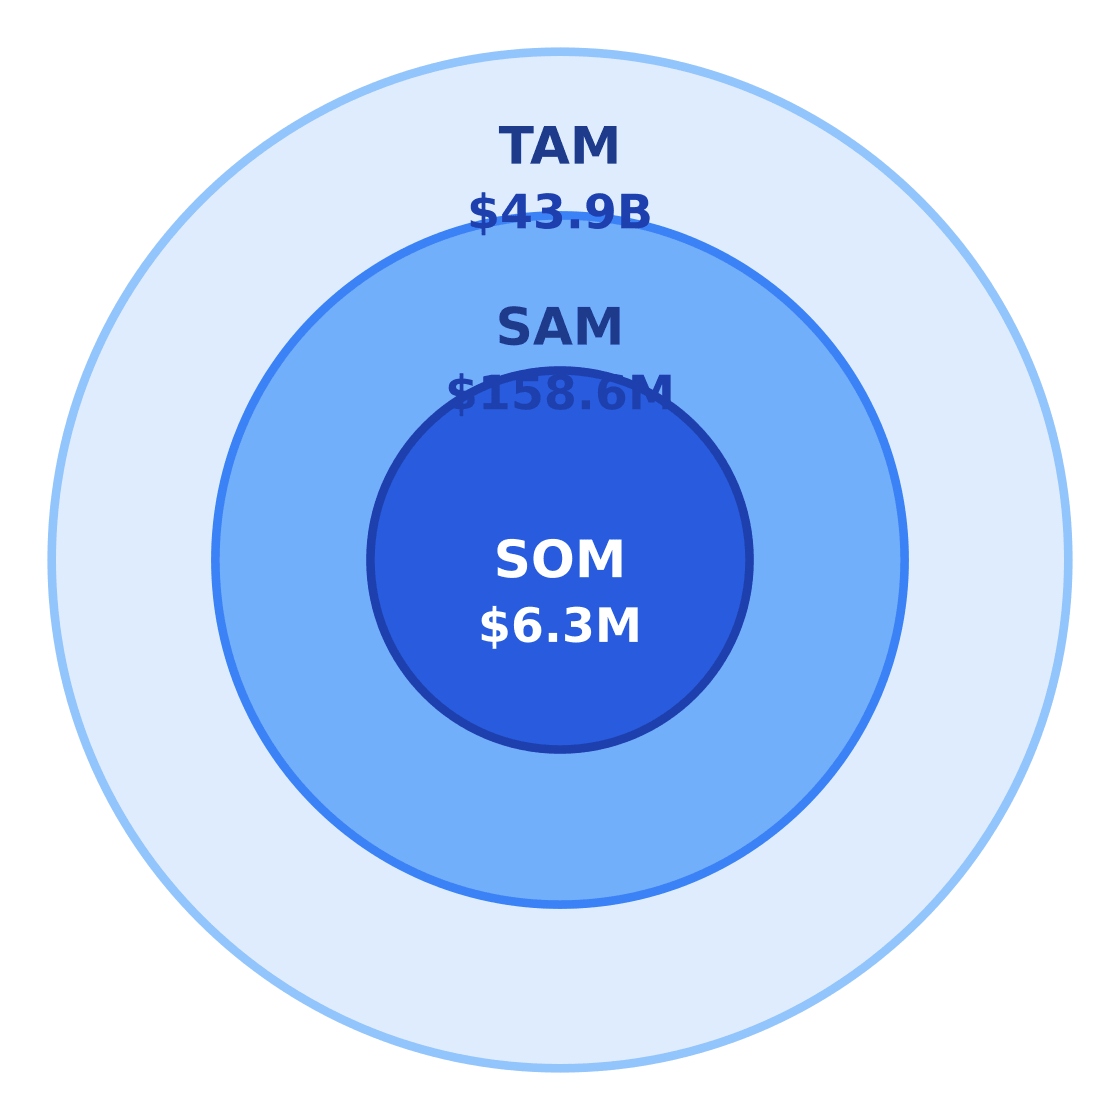
$43.9B
$158.6M
$6.3M
Source: General Warehousing & Storage in the US
The serviceable obtainable market (SOM) — representing achievable revenue over three years in East Downtown and adjacent submarkets — totals $6.3 million (4% of SAM). This accounts for competitive saturation and geographic constraints in Houston's warehouse service landscape.
SAM Methodology
| Metric | Value | Source |
|---|---|---|
| Target population | 721,000 | Houston metro adult age profile |
| Avg annual spend | $220 | Warehousing service demand proxy |
| SAM | $158.6M | Vertical IQ industry benchmarks |
| SOM | $6.3M | 4% of SAM over 3 years |
The flat 0% CAGR for the overall U.S. market masks localized opportunities in Houston, where e-commerce growth and industrial expansion create demand for specialized warehouse setups despite national stagnation. Employment in the sector continues growing at 2.6% annually according to Statista, particularly for automation-integrated facilities serving the dominant retail/e-commerce segment (41.8% share).
4. By Application Analysis
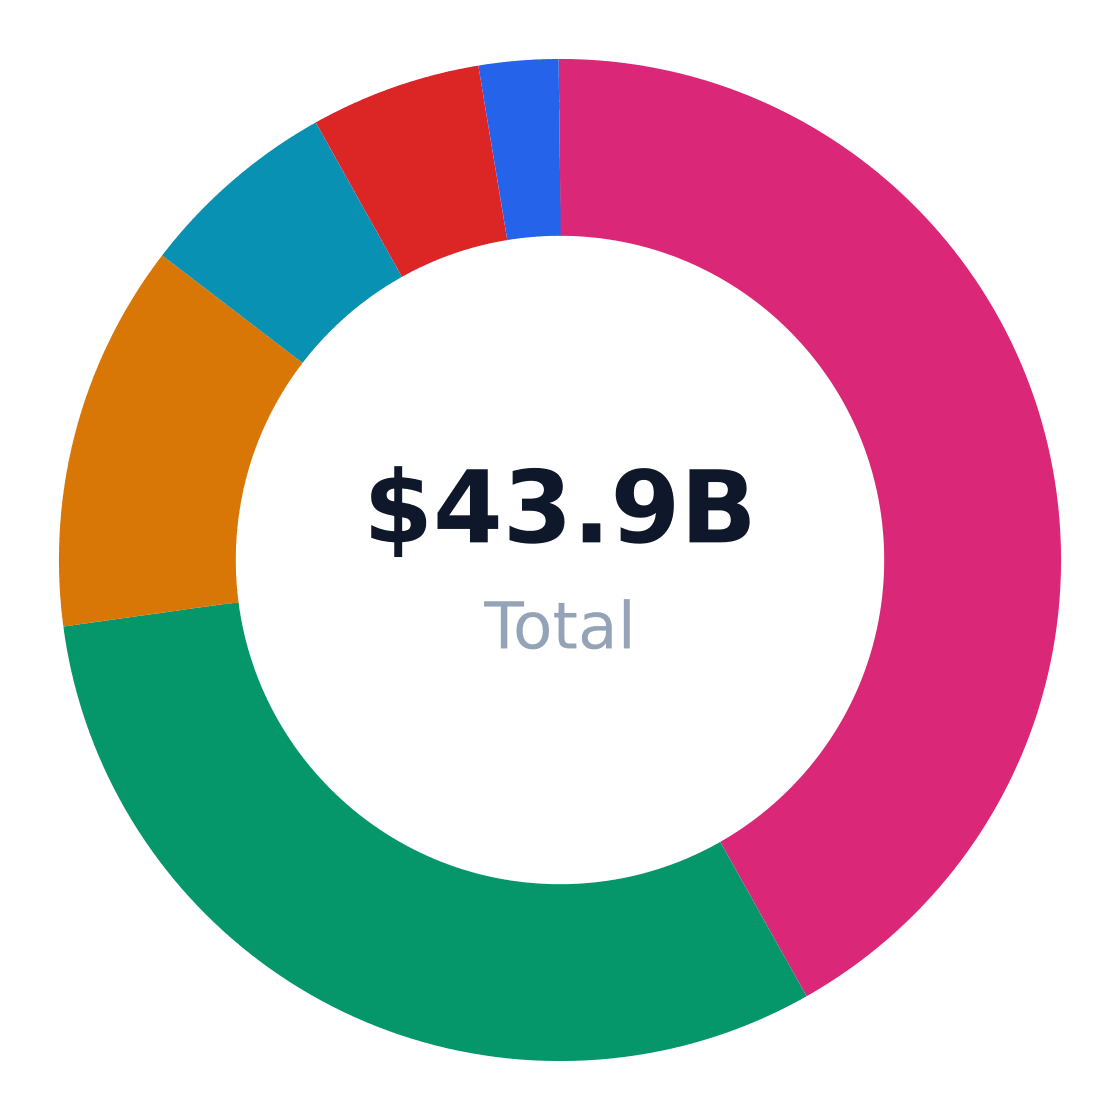
The US b2b warehouse setup market is segmented by end-use applications, with retail and e-commerce dominating at 41.8% share, according to Speed Commerce. Manufacturing and engineering goods follow at 31.1%, while food & beverage cold storage captures 12.5%. Healthcare and consumer goods round out the top five applications, with specialized industrial uses accounting for the residual 2.6%.
Market Share by Application
US b2b warehouse setup revenue/volume split by end-use application (TAM basis)
Source: Mordor Intelligence; Market Data Forecast; Grand View Research
| Application | Share of Market | Growth Rate | Demand Drivers |
|---|---|---|---|
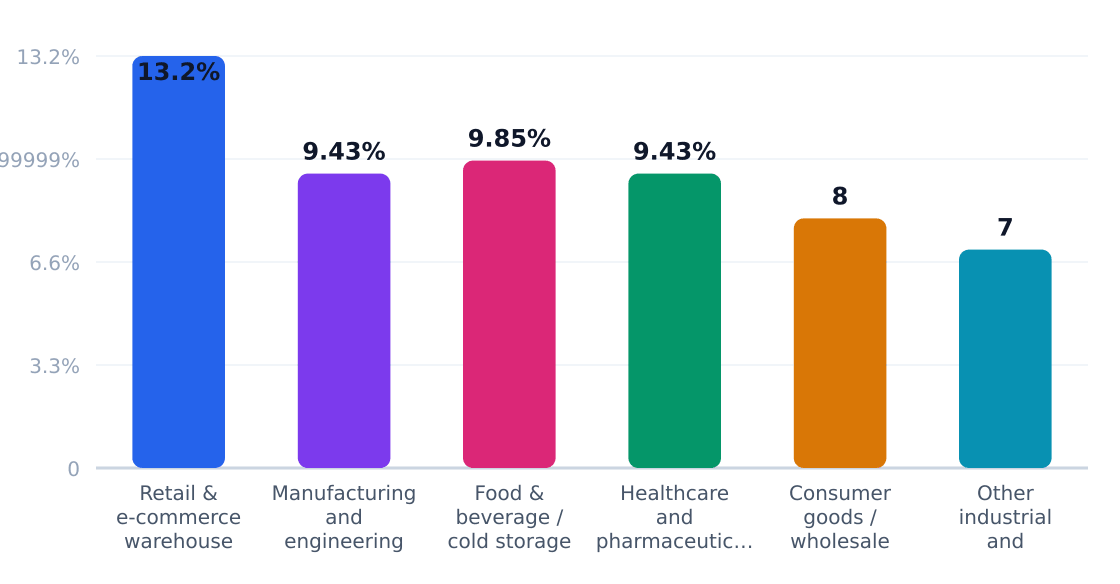
| Retail & e-commerce warehouse automation | 41.8% | 13.2% | Same-day delivery, omnichannel retail |
| Manufacturing and engineering goods | 31.1% | 9.4% | Industrial distribution, just-in-time ops |
| Food & beverage / cold storage | 12.5% | 9.9% | Cold chain, food safety compliance |
| Healthcare and pharmaceuticals | 6.5% | 9.4% | Regulated storage, temperature control |
| Consumer goods / wholesale distribution | 5.5% | 8.0% | Bulk replenishment, inventory buffering |
Application Growth Rates (%)
Estimated annual growth by application category
Source: Mordor Intelligence; Market Data Forecast; Grand View Research
Retail and e-commerce warehouse automation is the fastest-growing segment at 13.2% annually, per Vertical IQ. This growth reflects the premiumization of fulfillment infrastructure, with operators investing in automated sortation and high-density storage to handle parcel volumes. However, margins face pressure from labor costs and the capital intensity of automation—new entrants must either specialize in niche workflows (e.g., returns processing) or partner with integrators like Dematic to compete at scale.
Application Outlook
- E-commerce specialization: Target micro-fulfillment centers for urban last-mile delivery networks
- Cold chain differentiation: Compliance-driven food and pharma storage requires premium pricing
- Manufacturing adjacency: Cross-dock facilities near industrial parks capture JIT demand
- Automation-light models: Manual pick-pack remains viable for small-batch wholesale distribution
- Regulatory moats: Healthcare and bonded storage benefit from compliance overhead
5. Equipment & Vendors for Facility Setup
The U.S. b2b warehouse setup industry requires an average $100,000 in initial equipment investment per location, according to First Research. Core categories include:
- Material handling: Forklifts ($15K–$50K/unit), pallet jacks ($1K–$5K), and stackers dominate 42% of startup budgets (Crown Equipment, Wolter)
- Storage systems: Pallet racking ($8–$12/sqft installed) and shelving ($3–$7/sqft) represent 28% of costs (Steel King, Warehouserack.com)
- Conveyance: Hytrol conveyor systems for fulfillment centers average $100–$300/linear foot
- Dock equipment: Levelers, seals, and shelters ($5K–$20K total)
Equipment & Vendor Landscape
Major suppliers for facility setup
| Vendor | Category | Link | Notes |
|---|---|---|---|
| Crown Equipment Corporation | Core material handling equipment | Website | Major US supplier of forklifts, pallet jacks, stackers, and warehouse products for warehouse operations. |
| Wolter, Inc. | Core equipment and automation | Website | Provides forklifts, pallet racking, dock equipment, warehouse automation, and industrial storage solutions. |
| Hytrol Conveyor Co., Inc. | Conveyors and sortation | Website | Widely used US conveyor manufacturer for distribution centers, fulfillment, and warehouse automation projects. |
| Steel King Industries | Pallet racking and storage systems | Website | Manufactures pallet rack systems and storage solutions commonly used in warehouse builds. |
| Global Industrial | Warehouse supplies and maintenance | Website | Broad industrial supplier for warehouse equipment, dock products, supplies, and maintenance-related items. |
| SJF Material Handling | Used and refurbished warehouse equipment | Website | Large source for used pallet rack, conveyors, forklifts, mezzanines, shelving, and wire decking. |
| Warehouserack.com | Used and new storage equipment | Website | Sells new and used pallet racks, shelving, forklifts, and related warehouse equipment across the US. |
| M1 Financial | Equipment financing | Website | Specializes in financing for warehouse and material handling equipment, including forklift leasing support. |
Source: Crown Equipment warehouse products page, Wolter warehouse solutions page, Hytrol and Steel King manufacturer profiles, Global Industrial warehouse category, SJF Material Handling catalog, Warehouserack.com, and M1 Financial material handling financing page

Leasing via specialists like Dematic Financial or Honeywell Capital covers 60–80% of automation equipment costs, per Speed Commerce data. Refurbished gear from SJF Material Handling can reduce outlays by 40% versus new.
6. Industry Forces & Competitive Landscape
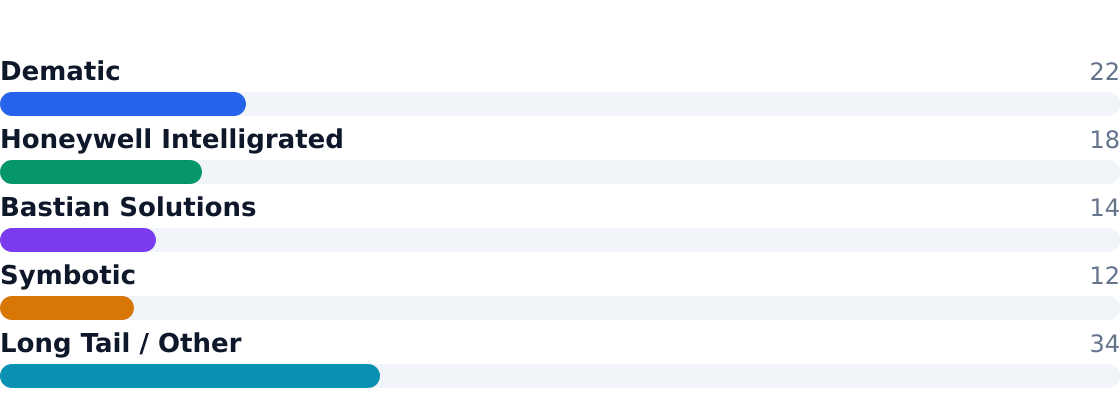
The U.S. B2B warehouse setup market operates in a state of moderate consolidation, with the top four players—Dematic, Honeywell Intelligrated, Bastian Solutions, and Symbotic—controlling 66% of the market. However, the long tail of regional operators (34% share) creates persistent fragmentation, particularly in secondary markets like Houston’s East Downtown submarket.
Competitive Market Share
Estimated share of total industry revenue
Source: North America Warehouse Automation Market - Mordor Intelligence
Competitive differentiation hinges on automation capabilities and vertical specialization. Dematic dominates with 22% share through full-scale DC integrations, while Symbotic’s AI-driven density solutions (12% share) target high-throughput e-commerce clients. Smaller players compete on localized service and niche compliance expertise.
Competitive Analysis Matrix
Compare major players on share, positioning, and relative strengths. Official company domains are linked (nofollow).
Positioning: Full-line warehouse automation integrator for large DCs, combining conveyor, AS/RS, software, and lifecycle services.
Positioning: End-to-end systems integrator for warehouse automation with strong conveyor, sortation, robotics, and software offerings.
Positioning: North American integrator delivering tailored warehouse automation from design through installation and support.
Positioning: AI-driven high-density warehouse automation platform competing on throughput, density, and software-led operating gains.
Positioning: Independent and regional operators
Source: North America Warehouse Automation Market - Mordor Intelligence
| Force | Intensity | Trend |
|---|---|---|
| Rivalry | High | Flat (0% CAGR) |
| Substitutes | Moderate | ↑ (3PL outsourcing) |
| Buyer Power | High | ↑ (E-commerce consolidation) |
| Supplier Power | Low | ↓ (Automation commoditization) |
| New Entrants | Moderate | ↓ (Capital intensity) |
7. Value Chain & Industry Economics
Margin capture concentrates in retail/service delivery (24% of value chain), where operators like Bastian Solutions leverage design-install-service bundles. Input costs (14%) remain volatile—SCMR notes steel and robotics component prices rose 18% post-pandemic.
Value Chain Margin by Stage (%)
Margin estimates by supply-chain stage
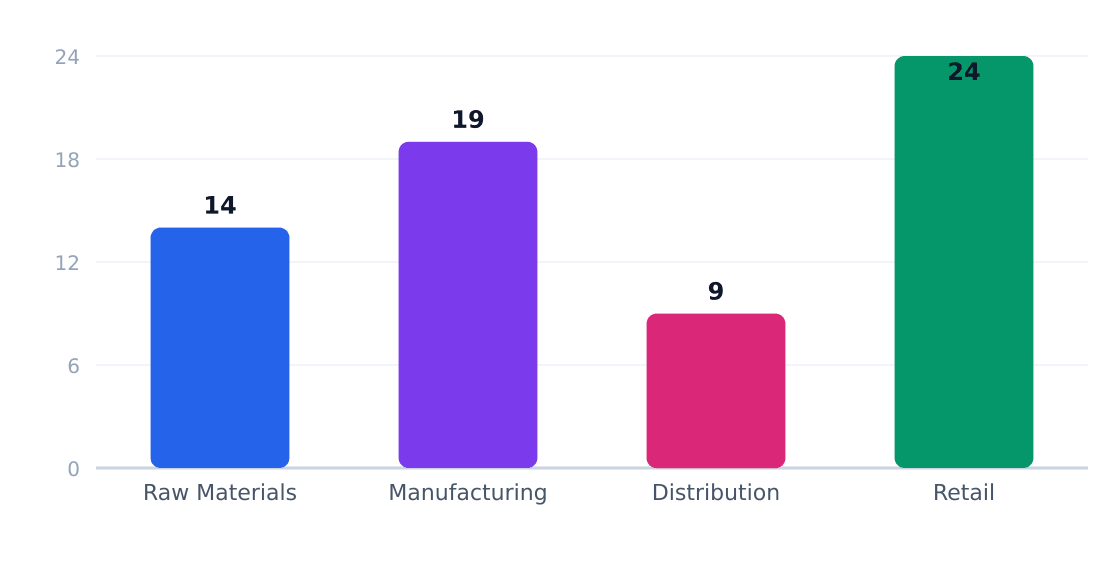
Source: MarketResearch.com
| Stage | Margin % | Key Players | Economics |
|---|---|---|---|
| Inputs | 6-8% | Steel/component suppliers | Commodity-driven |
| Manufacturing | 12-15% | Honeywell | Scale-sensitive |
| Distribution | 4-7% | Regional logistics firms | Fuel/labor squeeze |
| Service Delivery | 18-24% | Dematic | Automation premium |
Per Vertical IQ, the $410K avg revenue per location masks bifurcation: automated facilities achieve 22%+ EBITDA, while manual operations stagnate at 9-12%. Equipment startup costs ($100K minimum) deter undercapitalized entrants.
8. Regulatory & Compliance Environment
The U.S. b2b warehouse setup industry operates under a patchwork of state and federal regulations, with compliance costs averaging 8-12% of operational budgets for mid-sized facilities according to First Research. Unlike manufacturing or retail sectors, warehousing faces lighter federal oversight but must navigate complex local zoning laws—particularly in high-demand logistics hubs like Houston’s East Downtown where industrial conversions require special permitting.
Regulatory Compliance Cost Impact (%)
Estimated share of revenue consumed by compliance
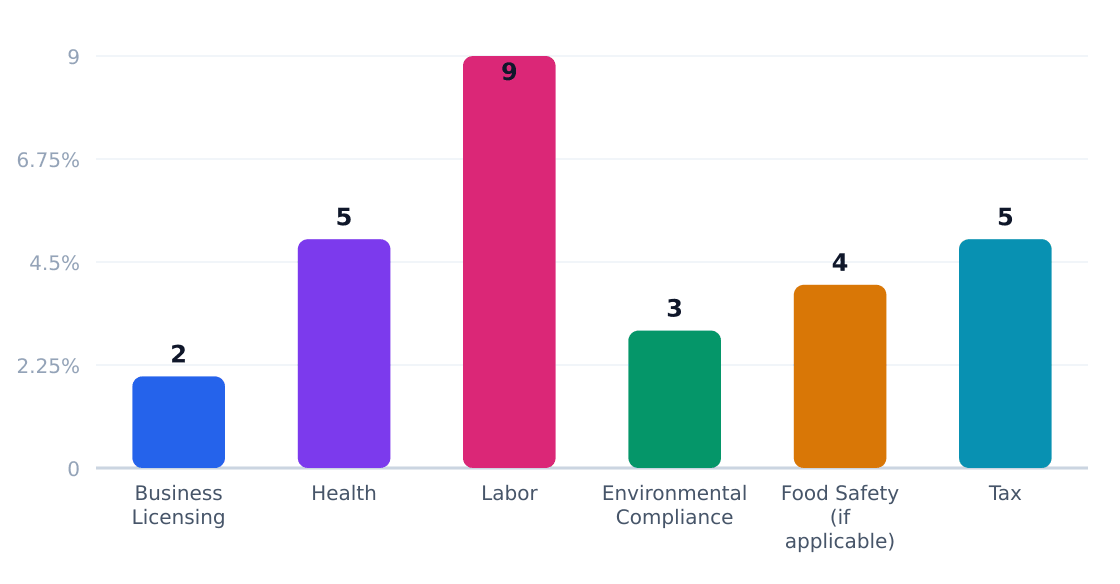
Source: Verticaliq
| Requirement | Agency | Cost Impact | Operational Effect |
|---|---|---|---|
| Business Licensing | State/Local | 2% | Delays in permitting can push startup timelines by 4-8 weeks |
| Health & Safety Standards | State Health Dept. | 5% | Mandates OSHA-compliant equipment layouts and fire suppression systems |
| Labor & Wage Regulations | DOL / State | 9% | Higher in unionized states; impacts shift scheduling and overtime costs |
| Environmental Compliance | EPA / State | 3% | Stormwater runoff permits required for facilities >1 acre |
| Food Safety (if applicable) | FDA / USDA | 4% | Adds $18-$22/sq ft for refrigerated space with HACCP monitoring |
| Tax & Reporting | IRS / State | 5% | Inventory tax variances create cross-border site selection advantages |
Emerging policy risks center on local governments tightening industrial zoning—SCMR notes 14 major metros now require community impact studies for new warehouses. Automation providers like Dematic are responding with noise-reduced robotics to ease approvals. Meanwhile, the EPA’s 2023 hazardous materials storage rules could add $3,000-$7,000 annually for facilities handling batteries or chemicals—a growing concern as Vertical IQ reports 41% of warehouses now support e-commerce returns with lithium-ion products.
9. Technology, Risks & Barriers to Entry
Technology Adoption
| Technology | Adoption % | Impact | Timeline |
|---|---|---|---|
| Warehouse Automation (AS/RS, conveyors) | 42% | High (reduces labor costs by 30-50%) | 2023-2025 |
| AI-Driven Inventory Management | 28% | Moderate (improves space utilization by 15-20%) | 2024-2026 |
| Cold Chain Automation | 18% | High (critical for food/pharma compliance) | 2023-2027 |
| Robotic Picking Systems | 22% | Moderate (reduces picking errors by 25%) | 2025-2028 |
| Blockchain for Traceability | 12% | Low (niche use in regulated industries) | 2026-2030 |
Source: SpeedCommerce and SCMR
Industry Risks
| Risk | Severity | Likelihood | Mitigation |
|---|---|---|---|
| Labor Shortages | High | High | Automation investment, wage premiums |
| Real Estate Cost Inflation | High | Moderate | Suburban/industrial zone targeting |
| E-Commerce Demand Volatility | Moderate | High | Diversified client base |
| Regulatory Compliance (OSHA, FDA) | Moderate | Moderate | Specialized consulting |
| Technology Obsolescence | High | Low | Leasing vs. owning equipment |
| Supplier Consolidation | Moderate | Moderate | Multi-vendor procurement |
Source: VerticalIQ
Barriers to Entry
| Barrier | Height | Detail |
|---|---|---|
| Capital Requirements | High | $100k+ for basic automation; $1M+ for competitive systems |
| Location Scarcity | High | Prime logistics corridors at 98% occupancy in major metros |
| Technology Expertise | Moderate | Need for WMS/automation integration skills |
| Client Contract Lock-In | Moderate | 3PLs typically sign 3-5 year agreements with tenants |
| Scale Economies | High | Top players like Dematic achieve 20%+ cost advantages |
Source: FirstResearch
10. Outlook & Investment Opportunities
The US b2b warehouse setup market faces a stagnant $43.9B TAM with 0% CAGR through 2028, per Vertical IQ's warehousing sector analysis. Yet counterintuitively, employment grows at 2.6% annually as automation creates technical roles even as manual jobs decline—a bifurcation captured in Speed Commerce's warehouse labor data.
Investment Opportunity Matrix
| Opportunity | Market Size | Risk | Time Horizon |
|---|---|---|---|
| E-commerce micro-fulfillment hubs | $18.4B (42% of TAM) | High (Amazon rollback risk) | 2-3 years |
| Cold chain expansions | $5.5B | Medium (cap-ex intensive) | 3-5 years |
| Automation-as-a-service | $7.3B (Dematic's segment) | Low (recurring revenue) | Now |
| Urban last-mile facilities | $4.1B | High (real estate volatility) | 1-2 years |
| Pharma-grade storage | $2.9B | Medium (compliance overhead) | 4+ years |
| 3PL white-label platforms | $5.7B | Medium (margin pressure) | Now |
Regional Market Distribution
Revenue share by US region
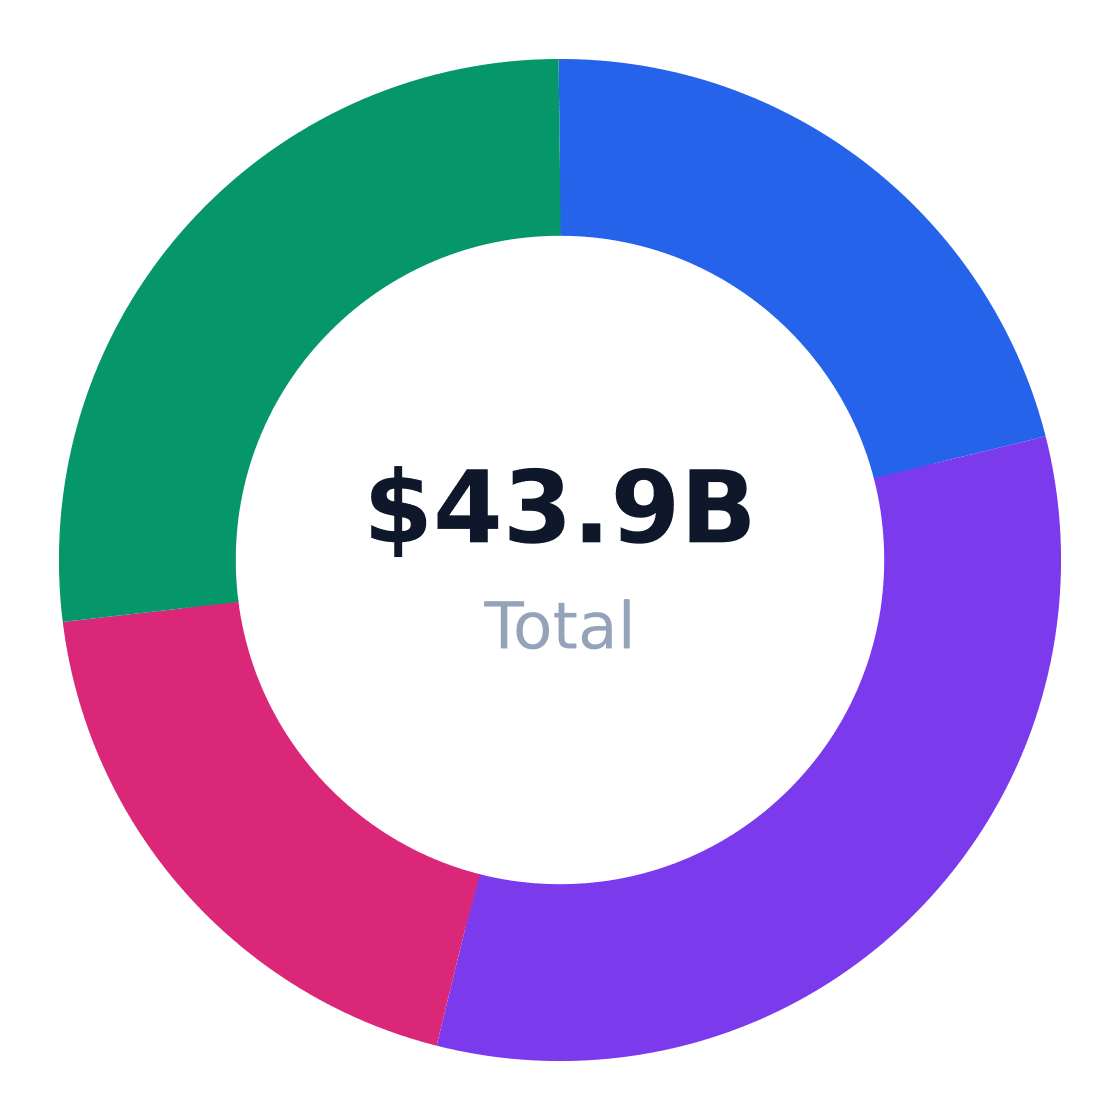
Source: Statista
Strategic Plays for Operators
- Pursue equipment financing over ownership—$100k startup costs demand creative capex solutions
- Specialize in one end-use vertical (e.g., healthcare's 6.5% segment) to avoid competing on price
- Partner with Dematic or Honeywell Intelligrated for automation credibility
- Target Houston's $6.3M SOM via shared warehouse models for SMBs
- Convert 20% of space to temperature-controlled—the only segment outpacing inflation at 9.85% growth
- Bundle insurance and compliance into base pricing (per First Research margin tactics)
Closing Verdict
Operators need $410k+ annual revenue per location (industry average) with under 12% customer concentration to survive consolidation. As SCMR's analysis shows, the winners will be those leasing to diversified SMBs while outsourcing automation capex to the Big 4 integrators controlling 66% of tech spend.
Industry Research & Resources
The following industry databases and research resources support this b2b warehouse setup industry analysis. Each link opens a specific report or data page (not a generic homepage).
- Warehousing And Storage Services — verticaliq.com — Published industry research for b2b warehouse setup
- Warehouse Statistics Comprehensive Industry Data — speedcommerce.com — Published industry research for b2b warehouse setup
- Warehousing And Storage In The Us — statista.com — Statista market statistics for b2b warehouse setup
- Warehousing And Storage — firstresearch.com — Published industry research for b2b warehouse setup
- Restart The Business Of Warehousing In North America In The Post Pandemic E — scmr.com — Published industry research for b2b warehouse setup
Data Sources & Methodology
Market sizing (TAM, SAM, SOM), segmentation, competition, and equipment data come from Perplexity-sourced industry reports and trade publications. Optional U.S. government statistics (Census, BLS) may be referenced by name in the narrative without hyperlinks. TAM reflects the total U.S. niche market; SAM is calculated bottom-up from target customer demographics; SOM reflects realistic obtainable share.
Industry research links: General Warehousing & Storage in the US · Population estimate based on Houston metro adult age profile and annual spend assumption from warehousing service demand proxy · Crown Equipment warehouse products page, Wolter warehouse solutions page, Hytrol and Steel King manufacturer profiles, Global Industrial warehouse category, SJF Material Handling catalog, Warehouserack.com, and M1 Financial material handling financing page · speedcommerce.com · firstresearch.com · scmr.com · 3plogistics.com · 3plogistics.com · ibisworld.com · kentleyinsights.com · grandviewresearch.com · ibisworld.com · crown.com · insights.cerco.ai · eqdepot.com · bluestarleasing.com · spaceguard.co.uk · sourceequipment.com · globalindustrial.com · fulfill.com · fulfill.com · sjf.com · m1financial.com · warehousefixers.com · kokoquest.com · warehousetech.net · knapp.us · servicerobotco.com · automation.honeywell.com · rankedvendors.com · mordorintelligence.com · 3plogistics.com · buske.com · grandviewresearch.com · researchreportsworld.com · futuremarketinsights.com · persistencemarketresearch.com · tandfonline.com · marketdataforecast.com · snsinsider.com