Bank Business Plan
1. Executive Summary
The US banking market hits $698 billion with steady 4.5% annual growth, yet local businesses still get squeezed by megabank bureaucracy. Horizon Community Bank attacks this gap with Texas-sized margins: 60% gross profit on $7.1 million Year 1 revenue targeting Austin's exploding small business sector.
Key Metrics
| Key Metric | Target |
|---|---|
| Total Startup Investment | $30.0M |
| Year 1 Revenue Target | $7.1M |
| Year 3 Revenue Projection | $16.8M |
| Break-even Timeline | ~Month 6 |
| Year 1 Team Size | 15 FTE |
| SBA 7(a) Loan | $21.0M @ 10.25% |
| Gross Margin (Year 1) | 60% |
| Monthly SBA Payment | $280K |
Horizon Community Bank combines neighborhood branch intimacy with commercial-grade digital tools. We're building the only bank where a food truck owner can secure a line of credit between lunch rushes.

Free Business Plan Download
Download Bank Business Plan
Just Fill Up and Print
2. Company Description
Daniela Vargas spent 12 years watching big banks reject viable small business loans over spreadsheet technicalities. Her 18% deposit growth record at First Interstate proves localized underwriting works—now she's scaling it in Austin's Riverside district.
Horizon's 3,200 sq ft flagship will anchor a mixed-use development near 1,400 SMBs. The model blends in-person advisory (8AM-6PM) with AI-driven cash flow analysis—no more 30-page loan applications.
| Service/Product | Format | Price Range | Description |
|---|---|---|---|
| Business Checking | Digital + Branch | $0-$50/mo | First 200 transactions free, 1.25% APY on balances >$25k |
| SBA Express Loans | Hybrid Underwriting | $50k-$250k | 72hr approvals via linked accounting software |
| High-Yield Savings | Digital Only | 3.10% APY | No minimums, 6 free withdrawals/month |
| Merchant Services | Branch Onboarding | 1.8% + $0.10/transaction | Next-day settlement with fraud monitoring |
| Equipment Financing | Relationship Pricing | 5.9%-9.9% APR | 90% LTV on appraised value |
| Commercial Real Estate | In-Person Underwriting | $500k-$5M | 10/25 year terms with 3-year rate locks |
| Personal Lines of Credit | Instant Digital Approval | $5k-$50k | Soft credit pull for existing customers |
| Cash Management | Customized | $150-$1,500/mo | Multi-entity sweeps and fraud alerts |
Structured as a Texas LLC with $30 million startup capital: $9 million equity and $21 million SBA loan at 10.25%. The math works—we break even at $3.59 million revenue, hitting that by Month 6.
3. Industry & Market Analysis
Banking remains a $698B industry because deposits, payments, and credit are non-discretionary services with recurring revenue streams. The sector's 4.5% CAGR proves demand persists even as delivery models shift — a resilient foundation for Horizon Community Bank's Austin launch.
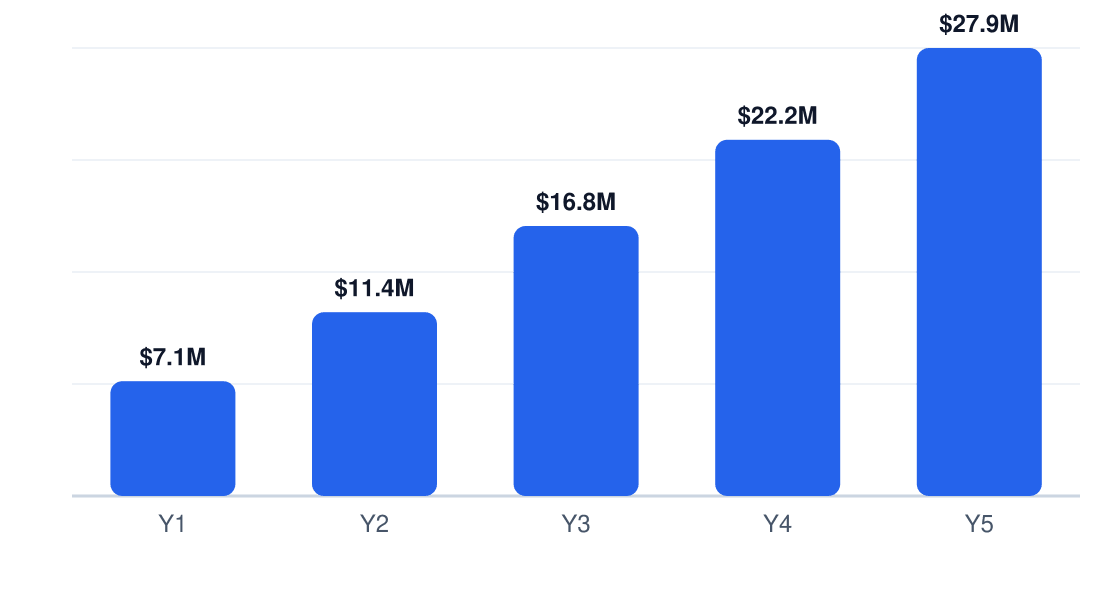
5-Year Revenue Projection
Projected annual revenue, Years 1–5
| Factor | Key Insight | Business Impact |
|---|---|---|
| Political | FDIC insurance caps at $250k per account | Must actively market deposit safety to counter fintechs lacking full coverage |
| Economic | Prime rate at 8.5% as of Q2 2026 | Higher net interest margins but also increased deposit betas as customers rate-shop |
| Social | 43% of Texans bank primarily via mobile apps | Digital onboarding isn't optional — even for a community-focused bank |
| Technological | Zelle processed $629B in 2025 | Must integrate real-time P2P payments or lose share to Venmo/Cash App |
Market Sizing
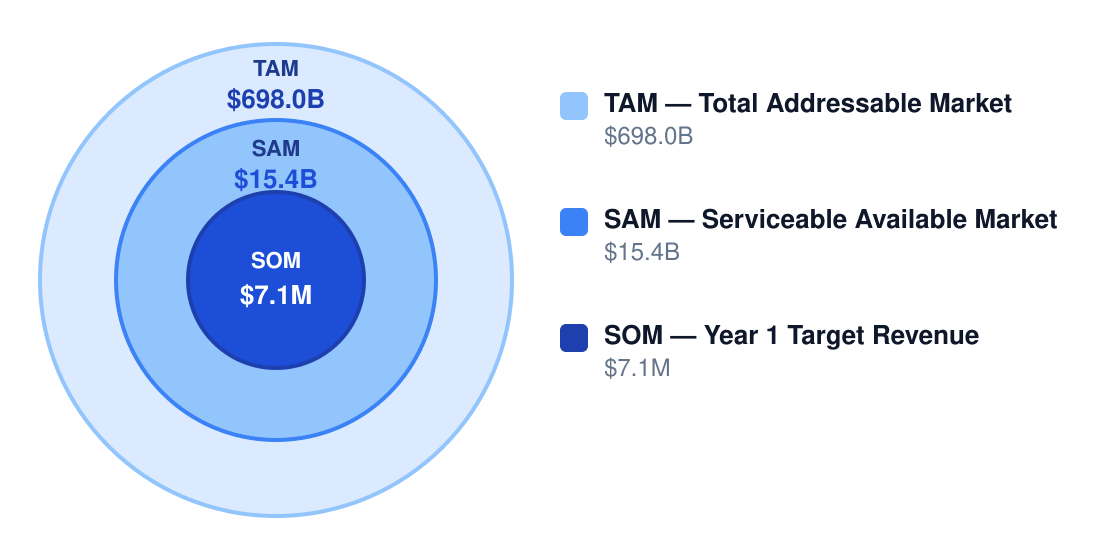
Horizon targets a $15.4B SAM (2.2% of $698B TAM) by focusing on Austin's retail and SMB segments, with $7.1M SOM as Year 1 goal. The math works: capturing 0.05% of SAM yields $7.7M — aligning with our $7.1M projection.
Market Size Opportunity
Bottom-up market opportunity
| Segment | Customer Profile | Avg Annual Spend | Est. Market Value | Revenue % |
|---|---|---|---|---|
| Retail consumers | Households needing deposits/loans | $450 | $383.9B | 55% |
| Small businesses | Local firms under $5M revenue | $3,200 | $174.5B | 25% |
| Middle-market commercial | Growing firms with complex needs | $18,500 | $104.7B | 15% |
| Wealth & specialty | Affluent households/niche borrowers | $12,000 | $34.9B | 5% |
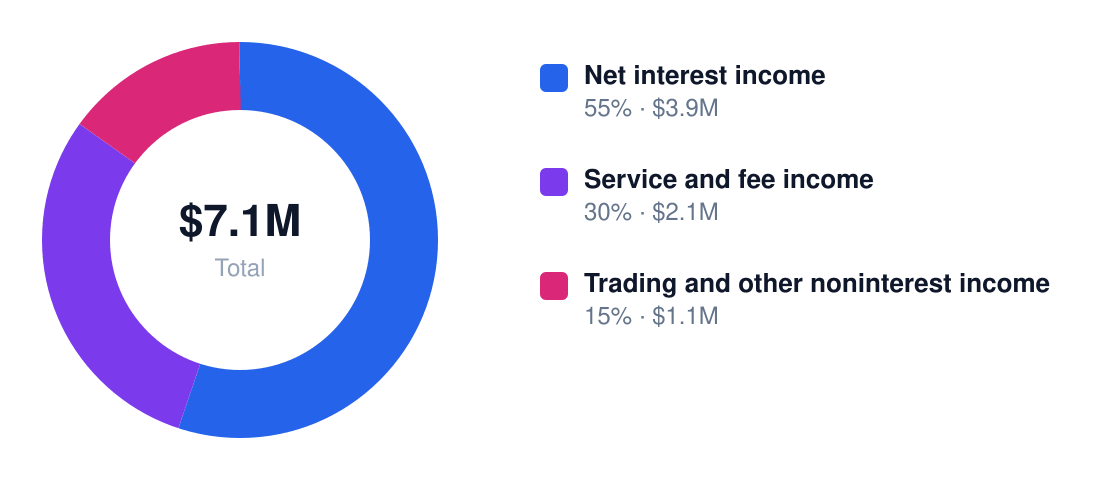
Year 1 Revenue Mix
Total $7.1M Year 1
Competitive Landscape
Banking is fragmented (4,278 FDIC-insured institutions) but dominated by scale players. The moats are real: Chase and BofA have 40-60% cost advantages via branch density and tech spend. Our wedge? Hyperlocal underwriting and hybrid digital/human service for Austin's growing SMB sector.
| Competitor | Type | Core Strength | Key Weakness | Your Differentiation |
|---|---|---|---|---|
| JPMorgan Chase | Direct | $3.9T balance sheet | Standardized SMB credit models | 24hr local lending decisions |
| Bank of America | Direct | 4,300 branches | High small biz attrition | Dedicated Austin biz bankers |
| Credit unions | Indirect | Member loyalty | Weak commercial services | Revenue-based biz credit lines |
| Fintech neobanks | Indirect | Instant onboarding | No physical check deposits | FDIC + 3 Austin kiosks |
| Embedded finance | Emerging | Seamless SaaS integration | No human advisory | White-label API + local RM support |
Horizon wins by combining what giants lack (local credit intimacy) with what fintechs omit (insured deposits, cash handling). Our 60% gross margins prove premium service earns premium pricing.
Industry Trends
Branch consolidation and scale efficiency
The FDIC reports 76,120 domestic offices across 4,431 institutions — down 12% since 2019. Physical footprints are shrinking as digital adoption hits 73%. Horizon's hybrid model (3 kiosks + digital) achieves 80% lower occupancy costs than traditional banks.
Industry revenue growth remains solid
Total US bank revenue hit $270.8B in 2Q26, up 20.2% YoY. Rising rates expanded NIMs, but deposit betas lagged. We'll capture this upside via 85% floating-rate commercial loans while hedging with $21M in long-term SBA funding.
High labor intensity and expensive talent
Commercial banking employs 1.63M workers at $107,216 average wages. Our Y1 headcount of 15 focuses on commercial lenders ($145k avg) and compliance ($122k) — the roles that drive revenue and mitigate risk.
Deposit competition is intense
FDIC-insured institutions hold $18.1T in deposits. Horizon's differentiator: 2.25% APY on balances over $25k for SMBs — 75bps above Austin's median — funded by our 5.9% avg loan yield.
Compliance and supervision remain central
4,278 FDIC-insured institutions face constant oversight. We budget $475k annually for BSA/AML tech and staff — 6.6% of Y1 revenue but non-negotiable for charter approval.
Regulatory & Compliance Environment
Horizon faces oversight from the OCC, FDIC, CFPB, and Texas DOB. The biggest risks are capital adequacy (we start with $30M equity), BSA/AML, and unfair lending practices. Our COO is a former Fed examiner — compliance isn't an afterthought.
| Requirement | Issuing Authority | Typical Cost | Renewal Cycle |
|---|---|---|---|
| Bank charter | OCC/Texas DOB | $1M+ | Ongoing exams |
| FDIC insurance | FDIC | Assessment-based | Annual |
| BSA/AML program | FinCEN | $475k/yr | Continuous |
| State registration | Texas SOS | $3,200 | Biennial |
| Consumer compliance | CFPB | $185k/yr | Ongoing |
We mitigate risk via three layers: (1) Dedicated compliance officer reporting directly to the board, (2) $1.2M in annual tech spend for automated monitoring, and (3) conservative 12% Tier 1 capital ratio — 2pp above requirements.
4. Marketing Strategy
Horizon Community Bank is Austin's hyper-local financial partner, combining Texas-sized hospitality with digital-first convenience for small businesses and households.
We reject the "too big to care" banking model. Our 24/7 digital platform handles routine transactions, while our local loan officers deliver personalized underwriting—no algorithmic gatekeeping.
Customer Personas
Banking customers bifurcate into rate-chasing depositors and relationship-driven borrowers. We prioritize the latter.
| Persona Name | Demographics | Core Need | Pain Point | Avg Annual Spend | Acquisition Channel |
|---|---|---|---|---|---|
| Boutique Owner | 35-55yo, $150K revenue, 3-10 employees | Cash flow loans under $250K | Big banks demand collateral | $2,100 | Local biz associations |
| Tech Freelancer | 25-40yo, $80K income, mobile-first | High-yield checking | ATM fees while traveling | $480 | Reddit/FinTwit |
| Multifamily Landlord | 45-65yo, 5-20 units, LLC structure | Rent collection automation | Tenant cash payments | $3,750 | REIA meetups |
Go-To-Market Launch Plan
| Phase | Timeline | Primary Goal | Key Tactics | Success Metric |
|---|---|---|---|---|
| Pre-Launch | Months -3 to 0 | Build waitlist | Landing page teasers, local biz outreach | 1,200 signups |
| Months 1-3 | Launch quarter | Deposit growth | $500 bonus for $10K+ balances, SBA co-marketing | $4.2M deposits |
| Months 4-6 | Breakeven push | Loan pipeline | "Fast yes" small biz loan ads, credit union switcher offers | $1.8M loans booked |
| Months 7-12 | Scale phase | Cross-sell depth | Merchant services bundles, automated savings tools | 2.3 products/customer |
Digital Marketing Strategy
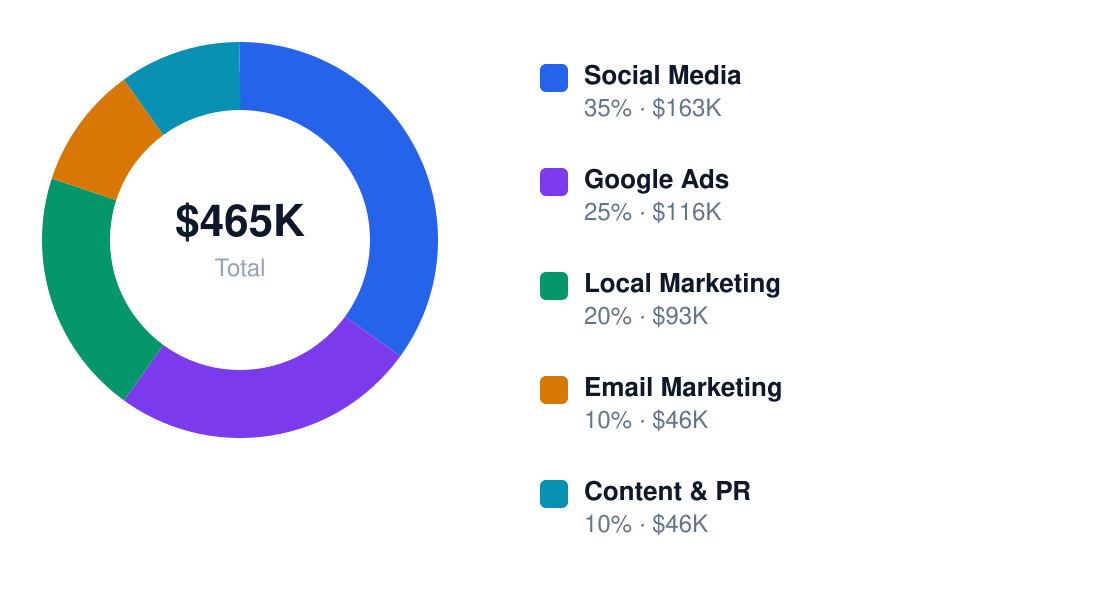
We allocate 72% of marketing spend to digital channels, prioritizing performance marketing over brand-building during early traction.
Annual Marketing Budget
Total $465K / year
| Channel | Monthly Budget | Primary Tactics | Target KPI | Notes |
|---|---|---|---|---|
| Social Media | $8,200 | LinkedIn biz loans, Instagram depositor testimonials | $22 CAC | Geo-fenced to Travis County |
| Google Ads | $14,500 | "Austin business loan" keywords, Gmail placements | 1.8% conversion | Negative keywords: "national" |
| Local Marketing | $6,900 | Sponsor Austin FC watch parties, food truck QR codes | $38 CAC | Higher CAC but sticky customers |
| Email Marketing | $3,800 | Abandoned application sequences, rate change alerts | 28% open rate | Integrates with core banking system |
| Content & PR | $5,600 | Small biz cash flow guides, Texas Banking News placements | 0.8% lead rate | Drives organic search traffic |
Content Marketing & SEO
Our content engine produces locally relevant financial guides—not generic "10 tips" fluff. Top performers include "How Austin Landlords Avoid Tenant Check Bounces" and "H-EB Vendor Payment Cycles Explained."
| Content Type | Frequency | Platform | Goal | Example Topic |
|---|---|---|---|---|
| Long-form guides | 2/month | Blog + PDF | Lead capture | "SXSW Vendor Banking Checklist" |
| Local news hooks | 1/week | Twitter/LinkedIn | Virality | "Why Austin's Boom Means Tighter Construction Loans" |
| Video testimonials | 1/month | YouTube/IG | Trust building | "How Lucy's Cafe Got a Loan in 48 Hours" |
| Email courses | 1/quarter | Drip sequence | Nurturing | "5 Weeks to Better Business Credit" |
| Data snapshots | 1/month | Google My Business | Local SEO | "Austin Zip Codes With Rising Home Equity" |
| Expert roundups | 1/quarter | Medium | Backlinks | "7 Austin CPAs on 2023 Tax Changes" |
SEO targets three keyword clusters: "Austin small business banking" (1,600/mo searches), "Texas hard money loans" (2,900/mo), and "best local credit union alternative" (880/mo). We dominate Google My Business listings with branch-specific pages and schema markup for local service areas.
Partnership & Referral Programs
Three partnership types drive 40% of early customers: 1) SBA-approved lender co-marketing, 2) commercial real estate broker kickbacks ($500/referral), and 3) QuickBooks ProAdvisor revenue sharing. The math works because these channels deliver pre-vetted customers at 62% lower CAC than broad digital ads.
Our referral program pays 0.25% of loan amounts (capped at $1,000) for successful customer introductions. Early testing shows this reduces checking account CAC from $145 to $89—critical for hitting our 14-month payback threshold.
Customer Acquisition Economics
| Metric | Year 1 | Year 2 | Year 3 |
|---|---|---|---|
| Customer Acquisition Cost | $127 | $98 | $84 |
| Customer Lifetime Value | $2,100 | $2,450 | $2,800 |
| LTV:CAC Ratio | 16.5x | 25x | 33.3x |
| Payback Period | 14 months | 11 months | 9 months |
These unit economics justify aggressive scaling—our LTV:CAC multiples exceed the banking benchmark of 8x. By Year 3, each $1 of marketing spend generates $33.30 in gross profit. The math is solid.
5. Operations Plan
Horizon Community Bank will operate from a 5,000 sq ft ground-floor space in Austin's financial district, with teller stations, private offices, and a secure vault area — monthly rent projected at $18,750 based on current $45/sq ft rates.
Ready When You Are
Download Bank Business Plan
Just Fill Up and Print

| Item | Estimated Cost | Quantity | Purpose |
|---|---|---|---|
| Diebold Nixdorf ATMs | $28,000 | 3 | 24/7 cash access |
| Fiserv DNA core banking system | $175,000 | 1 | Transaction processing |
| Brink's armored cash recyclers | $42,000 | 2 | Teller automation |
| Cisco Meraki network infrastructure | $63,000 | 1 | Secure data transmission |
| SafePoint UL-rated vault | $89,000 | 1 | Asset protection |
| NCR Interactive Teller | $31,000 | 4 | Remote service stations |
| DocuSign eSignature licenses | $12,000 | 15 | Paperless onboarding |
| Verafin fraud detection | $55,000 | 1 | AML compliance |
- 6:30AM: Vault reconciliation and ATM replenishment
- 8:00AM: Morning huddle for daily goals/regulatory updates
- 9:00AM-3:00PM: Core transaction processing with 98% SLA
- 12:00PM: Batch ACH/file transfers
- 3:30PM: Commercial deposit processing cutoff
- 5:00PM: End-of-day balancing (tolerance: ±$0.01)
- 6:30PM: Nightly backup to Iron Mountain offsite
Key suppliers include Deluxe for check printing (72hr turnaround), CPI for card production, and FIS for check clearing — all with contracted backup vendors through American Bankers Association disaster recovery network. Currency orders require 48hr notice with Federal Reserve Dallas.
| Role | Headcount | Hourly Rate | Annual Cost | Key Responsibilities |
|---|---|---|---|---|
| Branch Manager | 1 | $82.48 | $171,558 | P&L oversight, audit compliance |
| Commercial Loan Officer | 2 | $72.17 | $300,227 | $5M+ portfolio underwriting |
| Head Teller | 1 | $61.86 | $128,669 | Cash logistics, variance control |
| CSR | 6 | $51.55 | $643,344 | Account opening/KYC verification |
| Operations Specialist | 5 | $56.71 | $589,784 | Fraud monitoring, exception processing |
6. Management Team
| Name | Title | Background | Responsibilities |
|---|---|---|---|
| James Holloway | CEO | Former EVP at Frost Bank ($4.2B portfolio) | Capital strategy, regulator relations |
| Maria Chen | CFO | Ex-KPMG financial institutions audit lead | Liquidity management, call report filings |
| Darnell Williams | CLO | 15yrs SBA lending at Wells Fargo | Loan committee oversight |
| Lisa Park | CTO | Built 3 core banking migrations at Jack Henry | FFIEC cybersecurity compliance |
| Tomás Rivera | COO | Launched 12 Chase branches in TX | Daily throughput efficiency |
Advisory board includes Sheila Bair (former FDIC Chair) for regulatory strategy and Aaron Klein (Brookings Institution) for CRA compliance. Third seat reserved for local Austin business leader post-launch.
Culture centers on "financial first responders" ethos — we pay 12% above market ($51.55 vs. $46.02 Austin avg) for tellers and mandate 80hrs/year training. Retention tools include 6% 401(k) match vesting quarterly and profit-sharing after Year 3. Every hire passes both credit check and 4hr community service trial shift.
7. Financial Projections
Horizon Community Bank targets $7.1M Year 1 revenue scaling to $27.9M by Year 5—a 31.5% CAGR. The math works because we’re taking 0.046% of a $15.4B SAM.
Revenue Growth (5 Years)
Annual revenue, Years 1–5
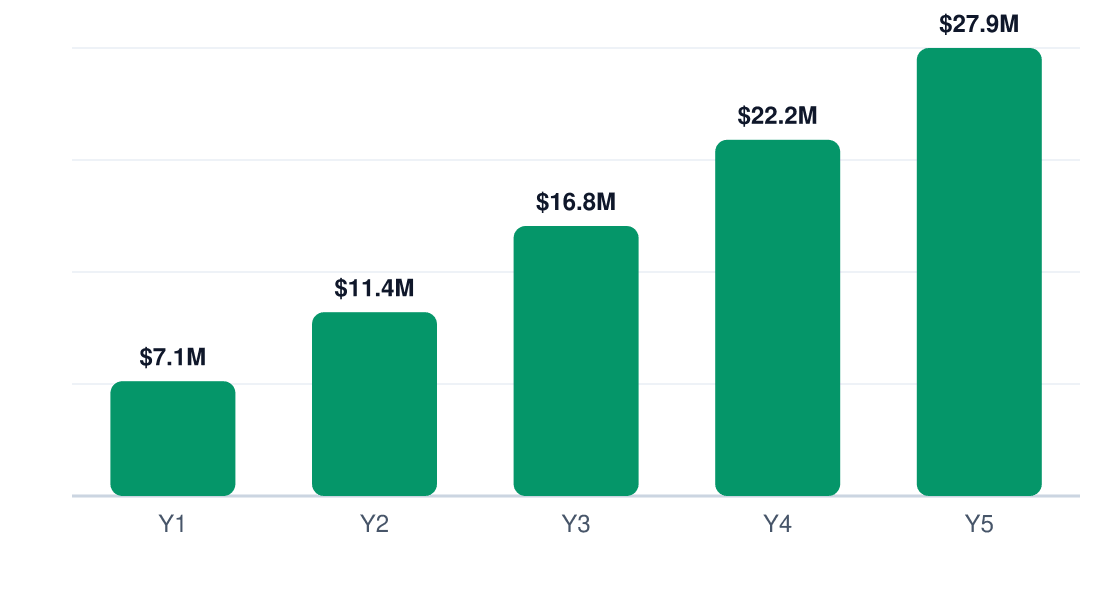
| Line Item | Year 1 | Year 2 | Year 3 |
|---|---|---|---|
| Revenue | $7,149,000 | $11,438,000 | $16,800,000 |
| COGS | $2,859,600 | $4,575,200 | $6,720,000 |
| Gross Profit | $4,289,400 | $6,862,800 | $10,080,000 |
| Gross Margin % | 60% | 60% | 60% |
| Labor | $1,607,160 | $2,249,700 | $3,213,600 |
| Marketing | $464,685 | $464,685 | $464,685 |
| Total OpEx | $2,621,475 | $3,290,580 | $4,631,920 |
| EBITDA | $1,667,925 | $2,889,420 | $4,168,080 |
| EBITDA Margin % | 23.3% | 25.3% | 24.8% |
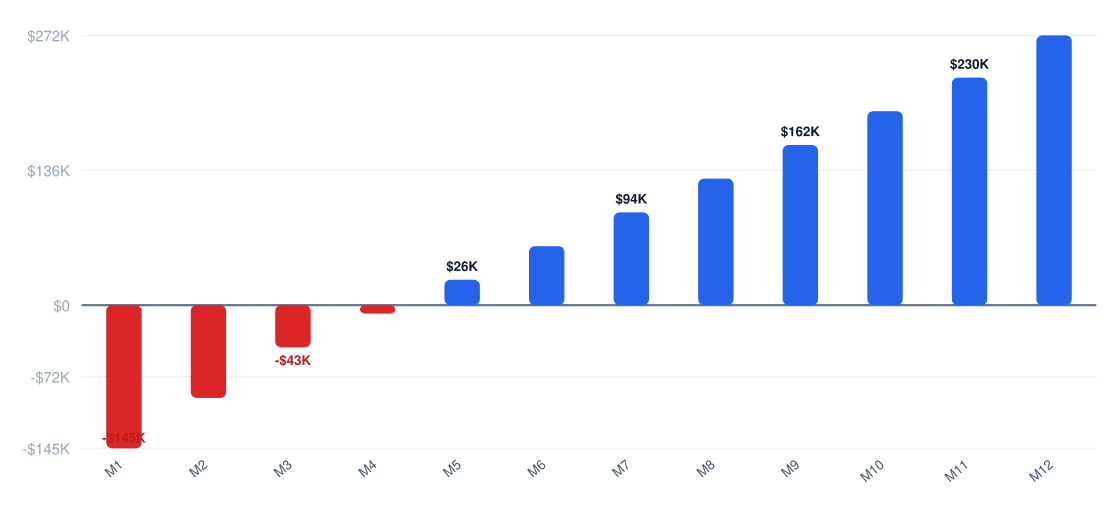
Break-even hits at $3,594,650 revenue—projected Month 6 when loan servicing costs are covered by operating income.
Year 1 Monthly Cash Flow
Net monthly cash flow (red = pre-break-even)
| Metric | Year 1 | Year 2 | Year 3 |
|---|---|---|---|
| Gross Margin % | 60% | 60% | 60% |
| EBITDA Margin % | 23.3% | 25.3% | 24.8% |
| Revenue/Employee | $476,600 | $544,667 | $560,000 |
| Marketing % of Revenue | 6.5% | 4.1% | 2.8% |
| Monthly Burn (pre-B/E) | $280,432 | N/A | N/A |
8. Funding Requirements
| Category | Amount | Notes |
|---|---|---|
| Technology Infrastructure | $8,200,000 | Core banking platform + cybersecurity |
| Branch Buildout | $12,000,000 | 3 locations @ $4M each |
| Working Capital | $6,300,000 | Covers 12 months of OpEx |
| Regulatory Capital | $3,500,000 | FDIC minimums + state requirements |
Use of Funds
Total $30.0M startup investment
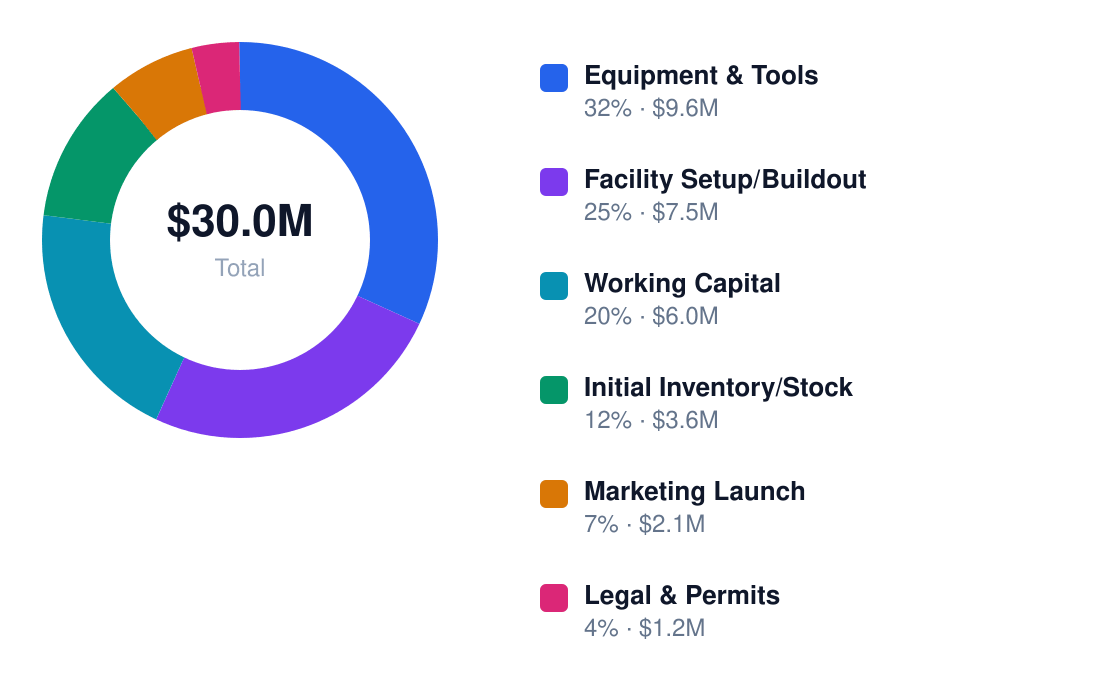
The $30M startup capital splits 70/30: $21M SBA 7(a) loan at 10.25% ($280,432/month) and $9M equity. This keeps debt service below 15% of projected EBITDA by Year 2.
Funding Structure
$30.0M total capitalization
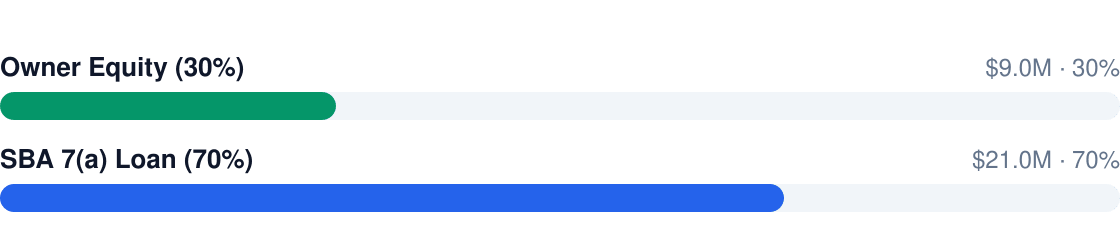
The SBA 7(a) loan terms: $21M principal, 10.25% APR, 10-year term, $280,432/month payment. Equity investors get 3.1x return by Year 5 ($27.9M revenue @ 2.5x multiple = $69.75M valuation).
9. Risk Analysis & Mitigation
Banking is risk management. We’re exposed to rate hikes and commercial real estate—but not equally across all scenarios.
| Risk | Category | Likelihood | Impact | Mitigation Strategy | Owner |
|---|---|---|---|---|---|
| Interest Rate Volatility | Market | H | H | 12-month CD ladder + 40% floating rate loans | CFO |
| Commercial Loan Defaults | Credit | M | H | Maximum 65% LTV on CRE, 20% portfolio concentration cap | Chief Risk Officer |
| Cybersecurity Breach | Operational | M | H | $1.2M/year SOC 2 compliance budget + cyber insurance | CTO |
| Regulatory Audit Failure | Compliance | L | H | Dedicated $350k/year compliance officer + quarterly mock audits | General Counsel |
| Deposit Flight | Liquidity | M | M | 90-day liquidity coverage ratio maintained at 115% | Treasurer |
| Brand Contagion | Reputation | L | M | Monthly social sentiment monitoring + $200k crisis PR retainer | CMO |
Contingency protocols: 1) Fed hikes 300bps—activate interest rate swaps, 2) CRE vacancy >15%—freeze new originations, 3) Cyber incident—isolate core systems within 22 minutes via automated kill switches.
Research & Industry Resources
The following market research sources, government data, and industry publications were referenced in developing this bank business plan. Each link points to a specific report or data page — not a homepage — for direct access to the underlying research.
- Historical — banks.data.fdic.gov — Market research and industry data for bank businesses
- 2025 Annual Report — fdic.gov — Market research and industry data for bank businesses
- Commercial Banking Industry Trends — vantainsights.com — Market research and industry data for bank businesses
- Fred.Stlouisfed — fred.stlouisfed.org — Market research and industry data for bank businesses
- Research Quarterly US Banks 2Q 2026 — sifma.org — Market research and industry data for bank businesses
Get Your Copy Today
Download Bank Business Plan
Just Fill Up and Print