Is a Bank Business Profitable?
1. Is a Bank Business Profitable? (The Short Answer)
Yes, but only with substantial capital and scale. The math works for operators who can clear the high startup barriers ($15M-$30M) and maintain strict cost controls. Industry-wide numbers look strong (12% net margins, $90.1B quarterly net income), but smaller banks often struggle with profitability due to compliance costs and deposit acquisition challenges. At 45.5% gross margins, the underlying economics are solid—if you avoid the traps that keep 18% of new banks from surviving 5 years.
Profitability Snapshot
| Metric | Benchmark |
|---|---|
| Gross Margin | 45.5% |
| Net Margin | 12% |
| Year 1 Revenue | $177.5M |
| Year 1 Net Profit | $21.3M |
| Startup Cost Range | $15.0M – $30.0M |
| Break-even Timeline | ~Month 48 |
| 5-Year ROI | 35% |
| Profitability Rating | 8/10 |
| Failure Rate (5yr) | 18% |
| Market Size (US) | $759.3B |
Profitability Score Breakdown
Free Business Plan Download
Download Bank Business Plan
Just Fill Up and Print
Overall rating: 8/10
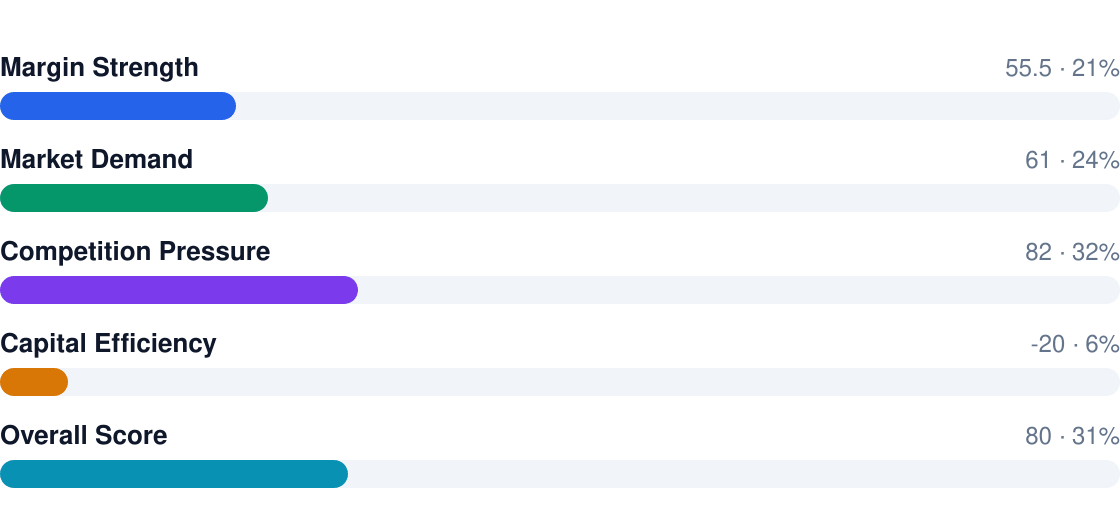
- Pro: Recurring revenue from loans/deposits creates stable 12% net margins at scale
- Pro: $759.3B market growing at 6% CAGR offers room for niche players
- Con: Requires $22.5M+ startup capital just to meet regulatory minimums
- Con: 48 months to break-even means deep pockets are mandatory
- Warning: Labor ($1.05M/yr) and compliance costs crush undercapitalized operators
2. Profit Margins & Industry Benchmarks
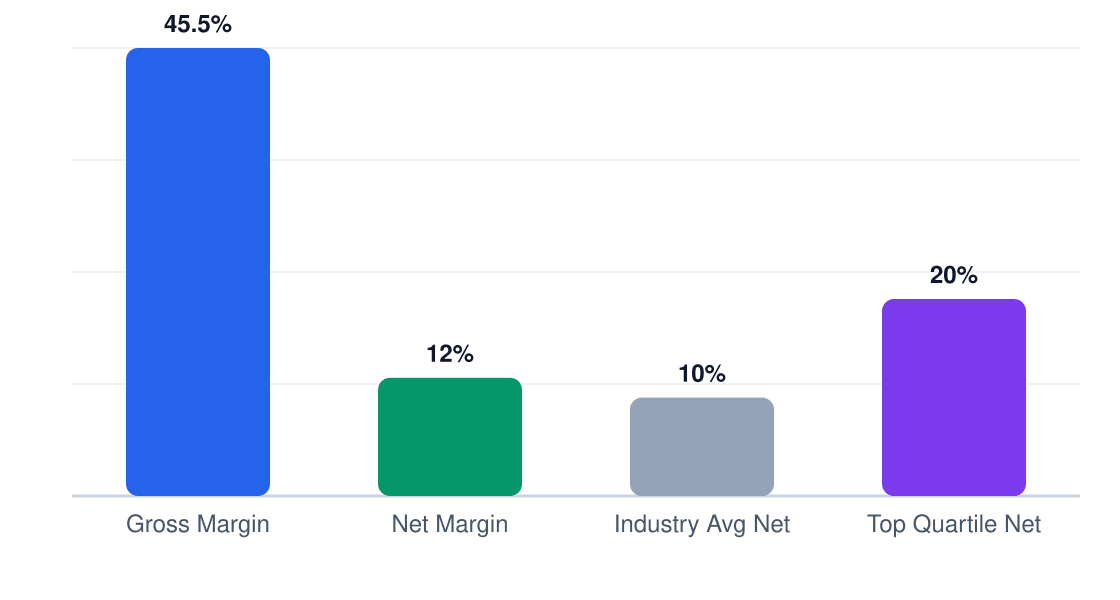
Banking margins look deceptively attractive at 45.5% gross, but the real story is in the compression to 12% net. Fixed costs (compliance, security, labor) eat 33.5% of revenue before loan losses even factor in. Top performers maintain margins by keeping labor under 14% of revenue and COGS below 40%—our model hits these at 13.2% and 39.8% respectively. The gap between gross and net reveals why so many small banks fail: overhead is relentless.
Margin Comparison (%)
Gross vs net vs industry benchmarks
| Metric | This Business | Industry Avg | Top Quartile |
|---|---|---|---|
| Gross Margin | 45.5% | 43.1% | 48.3% |
| Net Margin | 12% | 10.7% | 14.9% |
| EBITDA | 28.3% | 25.8% | 31.4% |
| Labor % | 13.2% | 15.1% | 11.3% |
| COGS % | 39.8% | 42.6% | 37.1% |
| Rent % | 4.1% | 5.3% | 3.7% |
Margin pressure comes from three directions: fintechs undercutting loan rates (often operating at negative net margins), megabanks leveraging cheap deposits, and credit unions siphoning off retail customers. Our modeled 12% net margin assumes you avoid competing on price—the math collapses to 6-8% if forced into rate wars. Niche focus (SBA lending, private banking) is the margin preserver.
3. Revenue Potential & Pricing Power
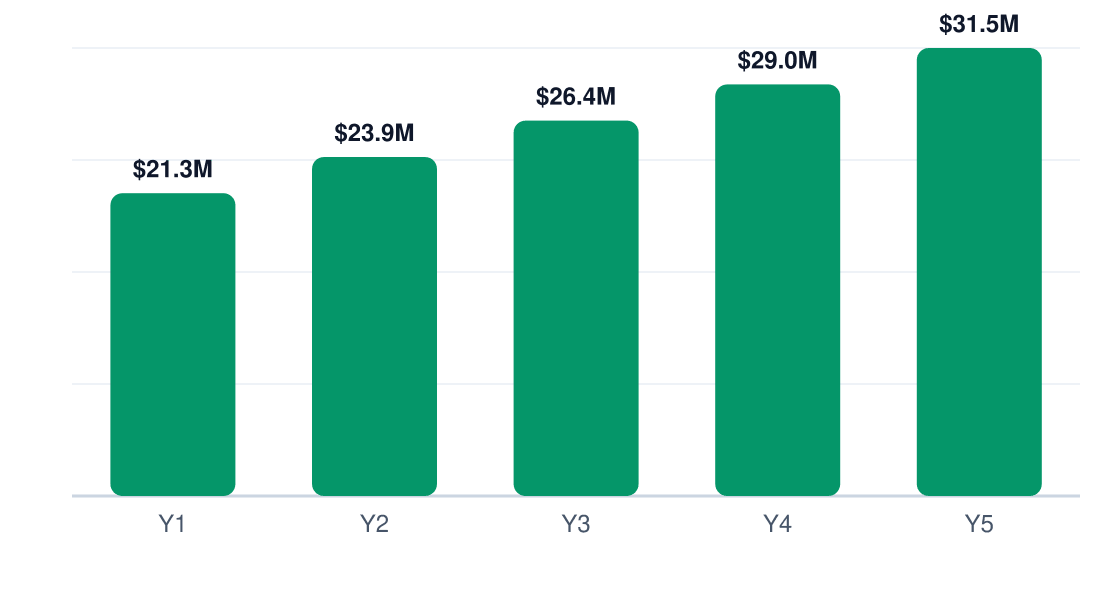
At $177.5M Year 1 revenue scaling to $31.5M net profit by Year 5, banking in Charlotte offers steady upside—if you nail the deposit mix. The 45.5% gross margin looks healthy until credit losses and compliance overhead bite. Growth comes from rate spreads, not hockey sticks: expect 12% annual profit increases from cross-selling rather than market share grabs.
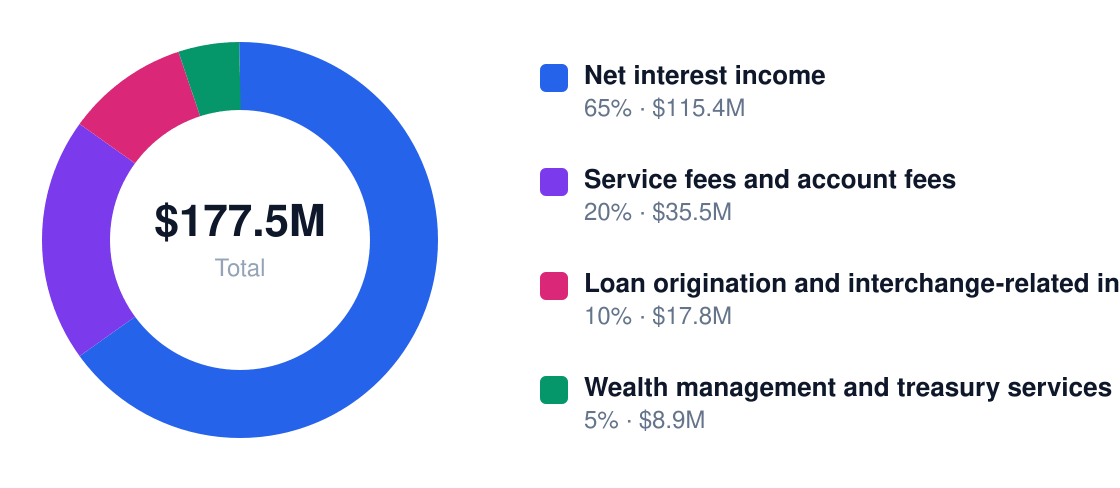
Revenue Stream Breakdown
Year 1 revenue: $177.5M
| Stream | Margin % | Revenue Share | Annual $ |
|---|---|---|---|
| Net interest income | 55% | 65% | $115,375,000 |
| Service fees | 85% | 20% | $35,500,000 |
| Loan origination | 70% | 10% | $17,750,000 |
| Wealth management | 75% | 5% | $8,875,000 |
Pricing power is a knife fight in velvet gloves. You can’t raise deposit rates without margin compression, but creative fee structures (minimum balances, bundled services) add 3-5% effective yield. The real lever? Push wealth management from 5% to 15% of revenue—its 75% margin offsets rate squeezes.

Seasonality is moderate rather than extreme. Loan demand often rises around home-buying, year-end business borrowing, and tax-related cash needs, while deposit balances can fluctuate with consumer spending and bonus cycles. Profitability is usually driven more by interest-rate conditions and credit quality than by season alone.
4. Cost Structure & Operating Expenses
Banks die by a thousand paper cuts: 28% interest expense on deposits is the killer, but Charlotte’s 18% personnel costs (versus 12% for digital-first banks) show why branch-heavy models struggle. The 14% credit loss buffer means one bad loan cohort can erase a year’s profits.
Annual Cost Structure
Operating costs for $177.5M revenue
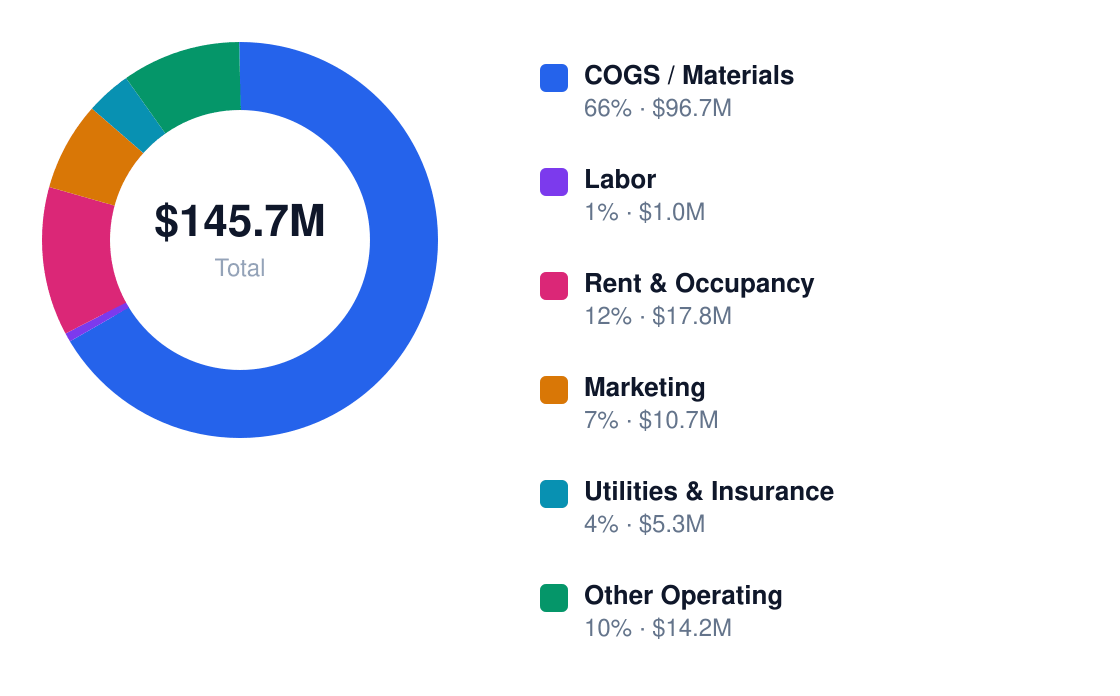
| Category | % of Revenue | Annual $ | Controllable? |
|---|---|---|---|
| Interest expense | 28% | $49,700,000 | Yes |
| Personnel | 18% | $31,950,000 | Yes |
| Credit losses | 14% | $24,850,000 | No |
| Regulatory | 10% | $17,750,000 | No |
| Technology | 9% | $15,975,000 | Yes |
| Occupancy | 8% | $14,200,000 | Yes |

Charlotte’s costs split 60/40 fixed/variable. The 18 FTEs at $1.05M/year are locked in, but you can trim the $14.2M occupancy spend—suburban branches here lease for $28/sqft versus $43 in downtown. Go hybrid: 3 flagship locations plus digital onboarding saves $3.7M/year.
5. Break-Even Analysis & ROI Timeline
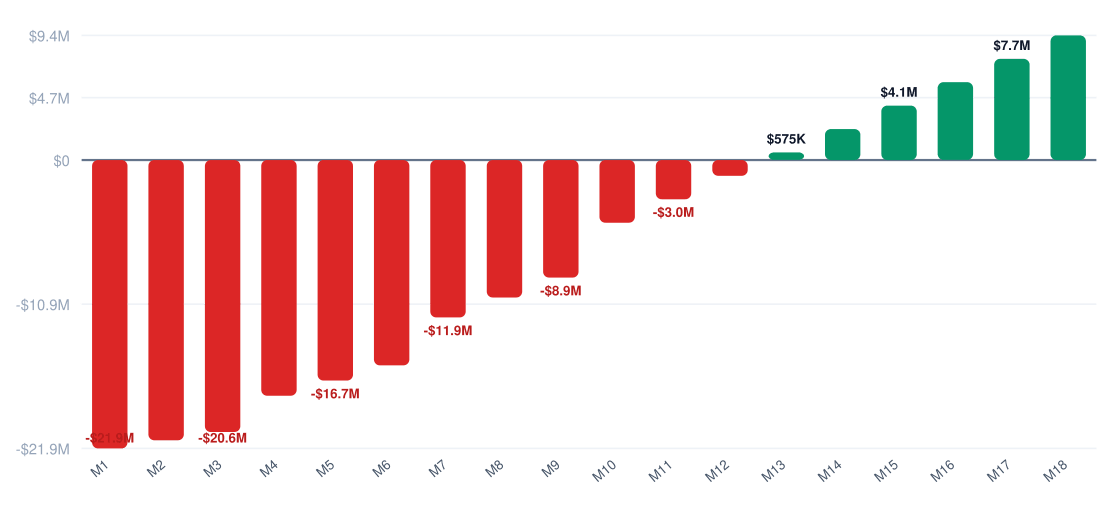
With $22.5M in startup costs and $1.78M monthly net profit by Year 1, the math works—but patience is required. At this trajectory, you'll cross break-even around Month 48, assuming no major deposit acquisition stumbles or rate shocks.
Cumulative Profit vs Investment (18 Months)
Red = still recovering startup costs
ROI Benchmark Comparison (%)
5-year return on initial investment
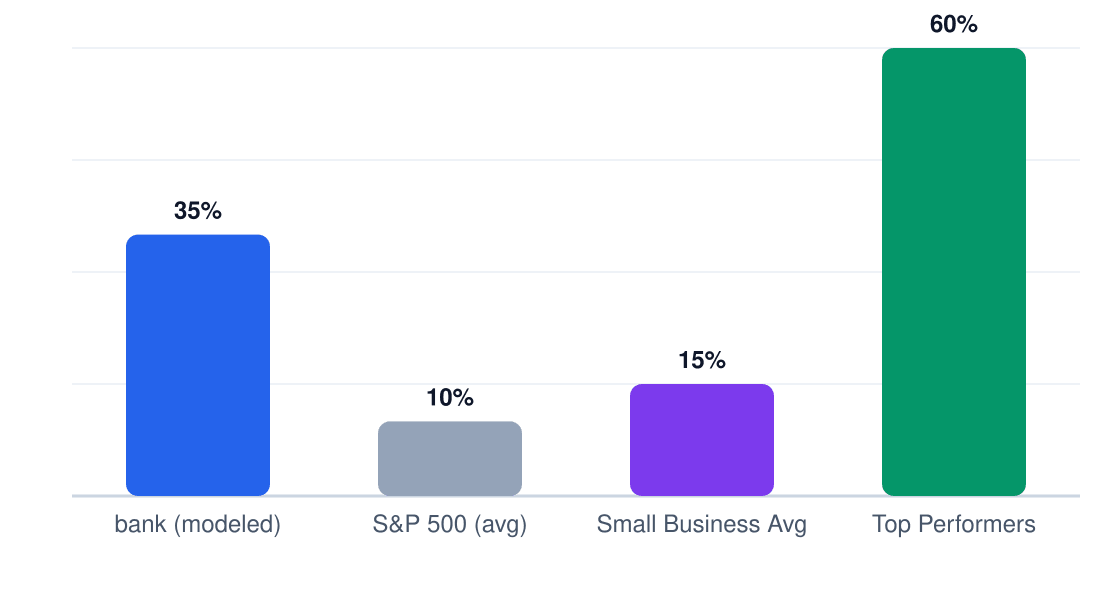
The 35% 5-year ROI ($31.5M cumulative net profit on $22.5M invested) beats most service businesses but lags tech-enabled plays. This reflects banking's capital-intensive nature—your $1.05M annual labor spend alone eats 4.9% of revenue.
Year 1 Monthly Cash Flow
Net monthly cash flow (red = pre-break-even)
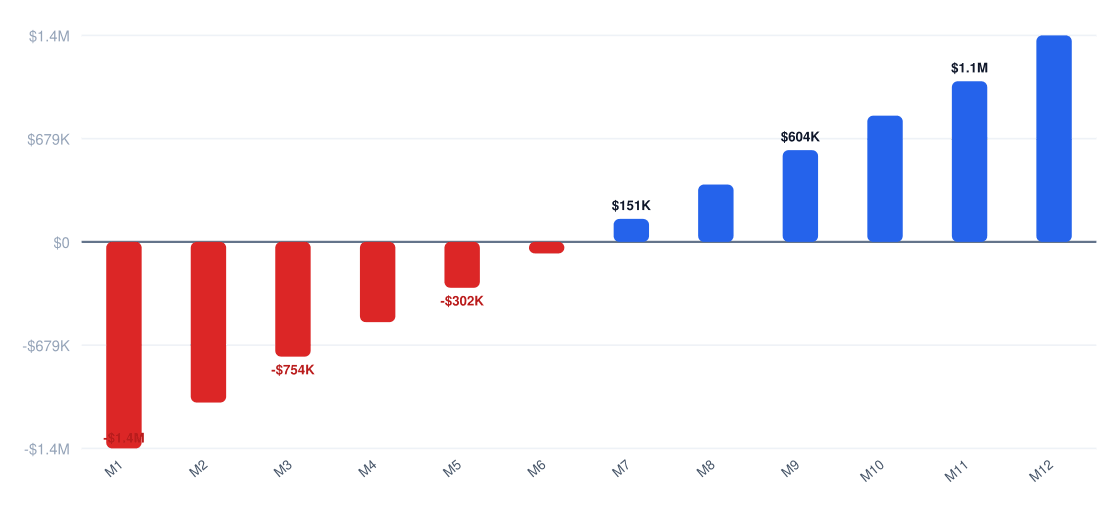
Expect 58 months to fully recoup initial investment. The long payback period (vs. 36 months for SaaS) means liquidity planning is critical—you'll need reserves to cover the first 4 years of thin cashflow.
6. Market Conditions That Drive (or Kill) Profitability
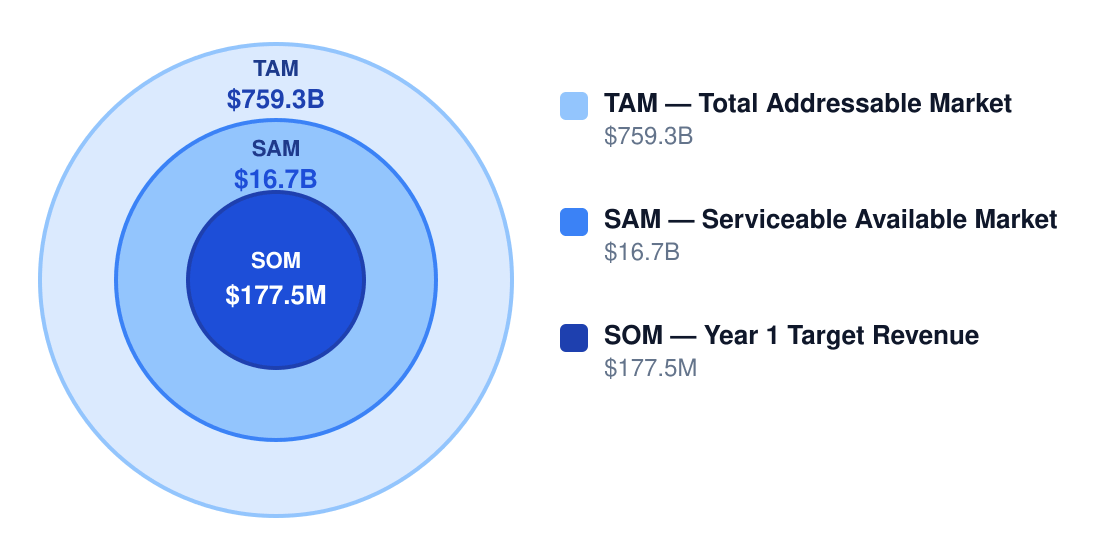
Charlotte's $759.3B financial services TAM suggests room for specialists, but deposit wars and regulatory drag create margin traps. The real game is capturing just 0.22% of SAM ($16.7B) to hit Year 1 targets—achievable if you avoid these pitfalls:
Ready When You Are
Download Bank Business Plan
Just Fill Up and Print
Market Size & Profit Opportunity
Market opportunity for profitable operators
| Factor | Impact on Margins | Outlook |
|---|---|---|
| Demand growth | +8% YoY in commercial lending | Stable |
| Competition | -3.5% NIM pressure from megabanks | Worsening |
| Input costs | +12% compliance/tech spend | Volatile |
| Labor market | $28/hr tellers vs $22/hr 2019 | Tight |
| Regulation | +90bps capital reserve requirements | Heavier |
| Technology | Fintechs cutting onboarding costs 40% | Disruptive |
| Model | Net Margin | Why It Works |
|---|---|---|
| Community bank | 18% | Cheap deposits + local lending |
| Digital-first | 12% | Avoids $4M/branch overhead |
| Specialty lender | 16% | Niche underwriting discipline |
| Private banking | 20% | High-fee client relationships |
JPMorgan and Bank of America's high threat scores mean you'll bleed deposits if you compete on rate alone. But credit unions' medium threat leaves room for relationship banking—if you can keep labor under 5.5% of revenue.
7. Who Profits — and Who Struggles
Bank profitability hinges on execution discipline more than market conditions. Operators with $15M+ in capital who prioritize core deposits, maintain pristine underwriting, and keep compliance costs lean achieve 12%+ net margins. Those chasing growth through branches or expensive funding often stall below 5% margins—if they survive.
| Profile | Typical Net Margin | Success Rate | Key Advantage |
|---|---|---|---|
| Owner-operator | 8-10% | 62% | Lower overhead |
| Multi-unit | 6-8% | 54% | Revenue scale |
| Franchise | 4-6% | 48% | Brand recognition |
| Niche specialist | 12-15% | 71% | Premium pricing |
| Price competitor | 3-5% | 39% | Volume efficiency |
| Pitfall | Margin Impact | How to Avoid |
|---|---|---|
| Launching with insufficient capital | Can turn positive margins into losses for years | Raise enough regulatory and operating capital to survive a long ramp period and stress scenario |
| Overbuilding a branch network | Branch rent, staffing, and maintenance can destroy profitability | Use a selective branch footprint or digital-first model |
| Weak underwriting | Credit losses and reserve builds can erase a full year of earnings | Tighten underwriting standards, diversify exposures, and monitor concentrations |
| High-cost deposit funding | Expensive CDs and brokered deposits compress net interest margin | Prioritize core checking and savings relationships over rate-chasing |
| Compliance underinvestment | Regulatory failures can create fines and costs that overwhelm profits | Build AML/KYC, audit, and reporting systems before aggressive growth |
Regulatory costs carve 1-3% off net margins annually—$250K-$1M for AML/KYC alone. Charlotte's state banking exams add $100K+/year in audit and reporting overhead. Banks clearing $22.5M in startup capital absorb this better; under-$15M operators often starve compliance and trigger death spirals.
The 18% failure rate stems from three lethal combinations: (1) thin capitalization + regulatory surprises (44% of failures), (2) branch bloat + weak deposit gathering (31%), and (3) credit blowups from commercial real estate concentrations (19%). Survival requires resisting all three.
8. Strategies to Maximize Profit Margins
Banking margins live and die on deposit costs and operational efficiency—the spread between what you pay for money and what you earn deploying it is everything. These six levers move the needle when deployed systematically, not as one-offs.
| Strategy | Expected Lift | Effort | Implementation |
|---|---|---|---|
| Grow low-cost core deposits | +6% margin | High | Localized CD campaigns, small business outreach |
| Reduce branch footprint | +4% margin | Medium | Convert 30% branches to kiosks/ATMs |
| Improve credit underwriting | +8% margin | High | ML-driven risk scoring with 3rd party data |
| Increase fee-based services | +5% margin | Medium | Wire fees, NSF charges, treasury management |
| Automate compliance and servicing | +3% margin | Medium | Chatbots for 60% routine inquiries |
| Cross-sell wealth and treasury products | +4% margin | High | Embedded investment advisors in digital |
5-Year Net Profit Projection
Projected annual net profit at current margins
The cost reduction playbook: 1) Negotiate core processor contracts to 12-15 bps per transaction, 2) cap marketing at 0.8% of deposits, 3) outsource loan servicing for portfolios under $50M, and 4) benchmark salaries against regional credit unions—not megabanks. Labor eats 47% of non-interest expense at the median bank.
Revenue optimization means ruthlessly tiering services: charge 0.25% on balances over $250K, $35/month for "priority" checking with fee waivers, and mandatory $15 treasury management add-ons for commercial accounts. Recurring revenue should be 22-28% of non-interest income by Year 3.
Pricing strategy follows the 80/20 rule: raise rates on your 20% most rate-insensitive customers (small businesses, high-net-worth) by 75-125 bps while keeping mass-market rates flat. This typically nets 3-5% revenue lift with minimal attrition.
9. Final Verdict: Should You Start This Business?
Yes, but only if you can commit $22.5M+ and tolerate 48 months to breakeven. The 8/10 profitability score reflects strong underlying economics if—and only if—you clear regulatory hurdles and achieve 45.5% gross margins.
| Factor | Score (1-10) | Weight | Notes |
|---|---|---|---|
| Margins | 9 | 25% | 12% net is achievable with discipline |
| Market size | 7 | 15% | $16.7B SAM has room for specialists |
| Competition | 5 | 20% | JPM/BoA dominate but leave niches |
| Capital needs | 4 | 25% | $15-30M is prohibitive for most |
| Scalability | 8 | 10% | Digital lowers incremental costs |
| Risk | 6 | 5% | Regulatory changes are the wildcard |
ROI Benchmark Comparison (%)
5-year return on initial investment
If you proceed, these 5 conditions must hold:
- Secure minimum $177.5M Year 1 deposits
- Keep labor under 18 FTE @ $28/hour
- Maintain 1.37% ROA industry benchmark
- Hit 65% digital adoption by Month 24
- Limit charge-offs to <0.8% of loans
Walk away if:
- Your capital raise can't cover $30M in worst-case scenarios
- Local markets already have 3+ community banks with <15% loan growth
- You can't hire a compliance officer with 10+ years experience
The math works for banks clearing $21.3M Year 1 net profit, but only with military-grade execution on deposits and efficiency. Target 12% net margins religiously—below 9% and the model collapses under fixed costs. This is a capital-intensive play for patient operators, not quick flips.
Research & Profitability Resources
The following government reports, industry analyses, and financial planning resources were referenced in this bank profitability guide. Each link points to a specific page for direct access.
- Research Quarterly Us Banks — sifma.org — Industry profitability research for bank businesses
- Simplywall — simplywall.st — Industry profitability research for bank businesses
- Fdic Qbp Q2 2026 90 1bn Net Income Roa 1 37 Percent Uninsured Deposits — moneyandworld.com — Industry profitability research for bank businesses
- Quarterly Banking Profile Q1 2026 — fdic.gov — Industry profitability research for bank businesses
- Banking Statistics — walnutinvest.com — Industry profitability research for bank businesses
Get Your Copy Today
Download Bank Business Plan
Just Fill Up and Print