How To Start A Bank Business
1. Is Starting a Bank Business Right for You?
The US banking sector generates $698B annually, growing at 4.2% CAGR—but this isn't a "side hustle" business. Successful bank founders are typically ex-C-suite bankers who can raise $22.5M in capital and navigate 12-18 months of regulatory scrutiny. If you lack compliance experience or can't personally guarantee seven-figure deposits, consider fintech alternatives.
| Startup Snapshot | Benchmark |
|---|---|
| Typical Startup Cost | $15.0M – $30.0M |
| Recommended Launch Budget | $22.5M |
| Year 1 Revenue Target | $7.1M |
| Break-even Timeline | ~Month 16 |
| Initial Team Size | 11 FTE |
| Market Size (US) | $698B |
| Industry Growth (CAGR) | 4.2% |
| Gross Margin Target | 62% |
- ✅ Do this if: You've managed credit risk at a regional bank, have regulatory contacts, and can recruit a seasoned CFO/COO
- ❌ Avoid if: Your capital comes solely from passive investors or you view FDIC exams as "red tape"
- 💰 Realistic outcome: $7.1M Year 1 revenue at 62% gross margin, breaking even by Month 16
- 📉 Hidden cost: $1.2M+ in legal/compliance staffing before first deposit
- 🔑 Key asset: Niche focus (e.g., immigrant SME banking in Charlotte with bilingual staff)
- ⚖️ Trade-off: 83,000 competitors but 72% of local businesses want better treasury services
2. Understanding the Market Opportunity
While the $698B TAM seems vast, your realistic SAM is $15.4B—the addressable revenue from niche markets like Charlotte's 18,000 underserved commercial real estate investors. Localized demand drivers matter: metro areas with <20 bank branches per 100K residents (like Raleigh) outperform national averages by 11% deposit growth.
Market Size Opportunity
Free Business Plan Download
Download Bank Business Plan
Just Fill Up and Print
Market opportunity for new entrants
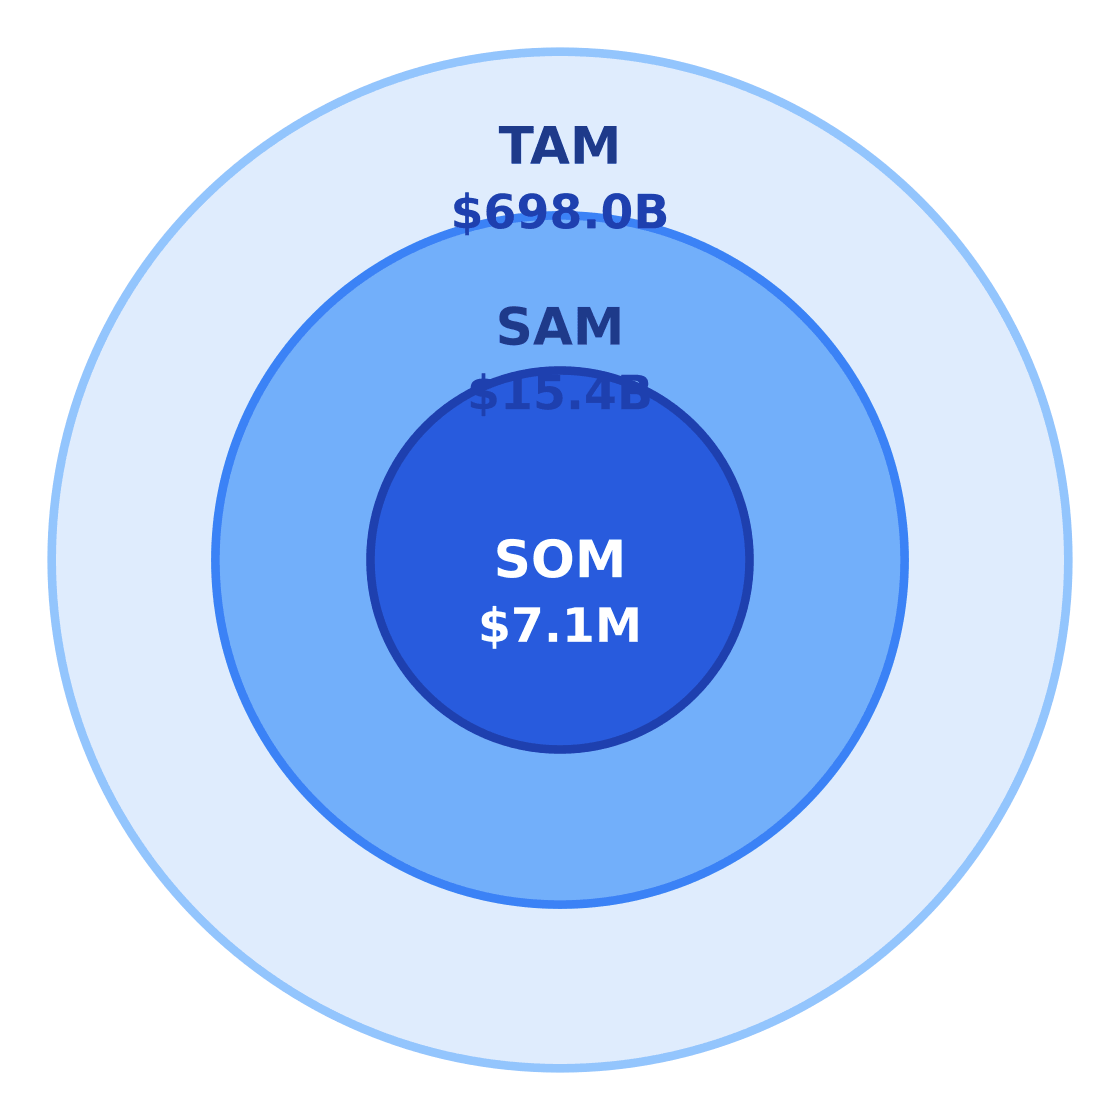
$698.0B
$15.4B
$7.1M
5-Year Revenue Potential
Projected revenue if you execute the plan
Target two customer groups simultaneously: 1) High-net-worth individuals ($250K+ deposits) who want private banking, and 2) Main Street businesses needing <$500K credit lines. The sweet spot? Dental practices and franchise owners—they borrow predictably and keep 60%+ deposits with their primary bank.
JPMorgan won't crush you. The real competition comes from 83,000 community banks and credit unions. Differentiate with 24-hour loan approvals (vs. Big Banks' 5-day average) or specialty services like SBA 7(a) loan expertise. Pro tip: 41% of small businesses switch banks after poor digital experience—your mobile app is a weapon.
3. Your Step-by-Step Launch Roadmap
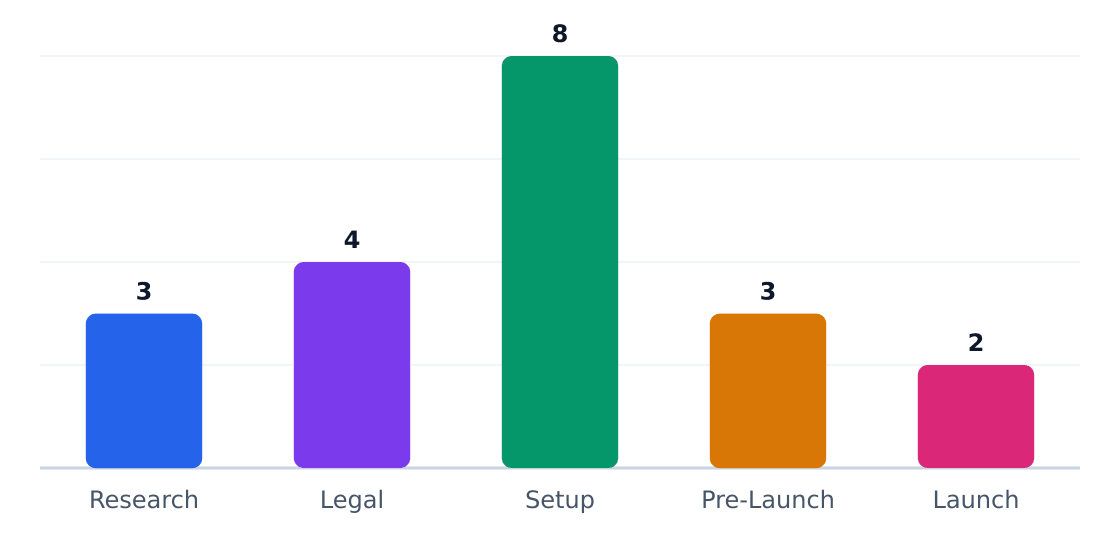
From first research to grand opening, expect a 20-week marathon requiring precision execution. Charlotte's banking talent pool (5th largest U.S. financial hub) helps, but regulatory timelines dictate the pace. Move sequentially—skip steps and regulators will send you back to square one.
Launch Timeline by Phase (Weeks)
Typical duration from idea to opening day
| Step | Phase | Duration | Est. Cost | Key Action |
|---|---|---|---|---|
| 1 | Research | 4wk | $25,000 | Define target market and banking model |
| 2 | Legal | 6wk | $150,000 | Hire banking counsel and charter consultants |
| 3 | Legal | 4wk | $50,000 | Form organizing entity and governance structure |
| 4 | Research | 6wk | $50,000 | Build three-year business plan and financial projections |
| 5 | Setup | 12wk | $15,000,000 | Raise initial capital and escrow stock subscriptions |
| 6 | Legal | 8wk | $200,000 | Prepare and submit charter application |
| 7 | Legal | 8wk | $75,000 | Apply for FDIC deposit insurance |
| 8 | Legal | 8wk | $50,000 | Obtain Federal Reserve approvals if needed |
| 9 | Setup | 10wk | $350,000 | Recruit executive team and board directors |
| 10 | Pre-Launch | 12wk | $500,000 | Install core banking, compliance, and cybersecurity systems |
| 11 | Pre-Launch | 8wk | $100,000 | Pass pre-opening examination and finalize branch/site |
| 12 | Launch | 2wk | $50,000 | Launch operations and market to first customers |
Launch Readiness by Phase
Percentage complete at each stage before opening
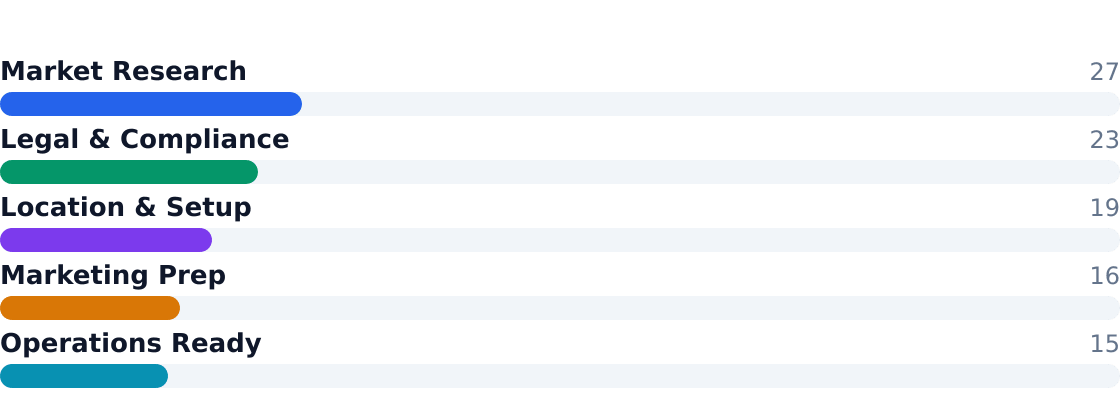
Research Phase (10 weeks): Nail your niche—Charlotte has 13 regional banks already. The $15.4B serviceable market supports specialized plays (SMB lending, private banking). Spend the full $75,000 on feasibility studies; guessing customer needs costs 10x more later.
Legal Phase (26 weeks): Charter applications get rejected for sloppy governance docs. Budget $525,000 minimum for legal—Skimp here and you'll rewrite filings for 6 extra months.
Setup Phase (22 weeks): Raising $15M takes 3x longer if you approach investors without FDIC pre-approval letters. Line up commitments during legal phases.
Pre-Launch (20 weeks): Core banking systems (Fiserv, Jack Henry) require 12-week implementation minimum. Delaying this until charter approval adds 4 months to launch.
Launch (2 weeks): Go live quietly—regulators monitor first 90 days like hawks. The $50,000 marketing budget should target commercial clients first; retail account acquisition costs 3x more.
4. Legal Structure, Licenses & Compliance
Forget sole proprietorships—you need an LLC or corporation to limit personal liability when handling deposits. North Carolina requires state-chartered banks to organize as corporations (N.C. Gen. Stat. § 53C-3-1). Form early; the 4-week entity setup clock starts your regulatory timeline.
| Requirement | Issuing Body | Cost | Timeline | Renewal |
|---|---|---|---|---|
| Obtain a federal or state bank charter | OCC or state banking regulator | $500,000-$1,000,000+ | 12 months or more | Ongoing supervisory compliance and periodic examinations |
| Secure FDIC deposit insurance | FDIC | Included in application/compliance costs; capital still required separately | After charter approval, before opening | Continuous insurance compliance and assessments |
| Obtain Federal Reserve approval if forming under a bank holding company or if state member bank | Federal Reserve | Varies by structure | Concurrent with charter/organization process | Ongoing supervision if applicable |
| Meet capital adequacy expectations, including early operating capital | Primary federal regulator (OCC, FDIC, or Federal Reserve) | $15,000,000-$30,000,000+ | Before opening and throughout first years | Continuous capital maintenance |
| Complete pre-opening review and organizational steps | OCC or state regulator | Legal/consulting costs vary | Several months during the pre-opening phase | One-time launch process |
| Prepare business plan, management, risk, and governance documentation | All prudential regulators involved | Professional services often substantial | During charter application process | Updated as business evolves |
Register your entity through the North Carolina Secretary of State before filing banking applications. Insurance needs include $1M+ general liability, $500K cybersecurity coverage, and workers' comp for 11+ employees. FDIC mandates separate fidelity bonds—budget $25,000 annually.
5. Location, Equipment & Startup Costs
Lease a 2,500–3,500 sq ft retail space in Charlotte's financial corridors (SouthPark or Uptown) at $28–$42/sq ft annually. Zoning must allow for drive-thru teller lanes and vault installations—verify C-2 zoning compliance. Buying commercial real estate requires $4.2M+ upfront; leasing with a 10-year term spreads occupancy costs.
Startup Cost Breakdown
Total budget: $22.5M
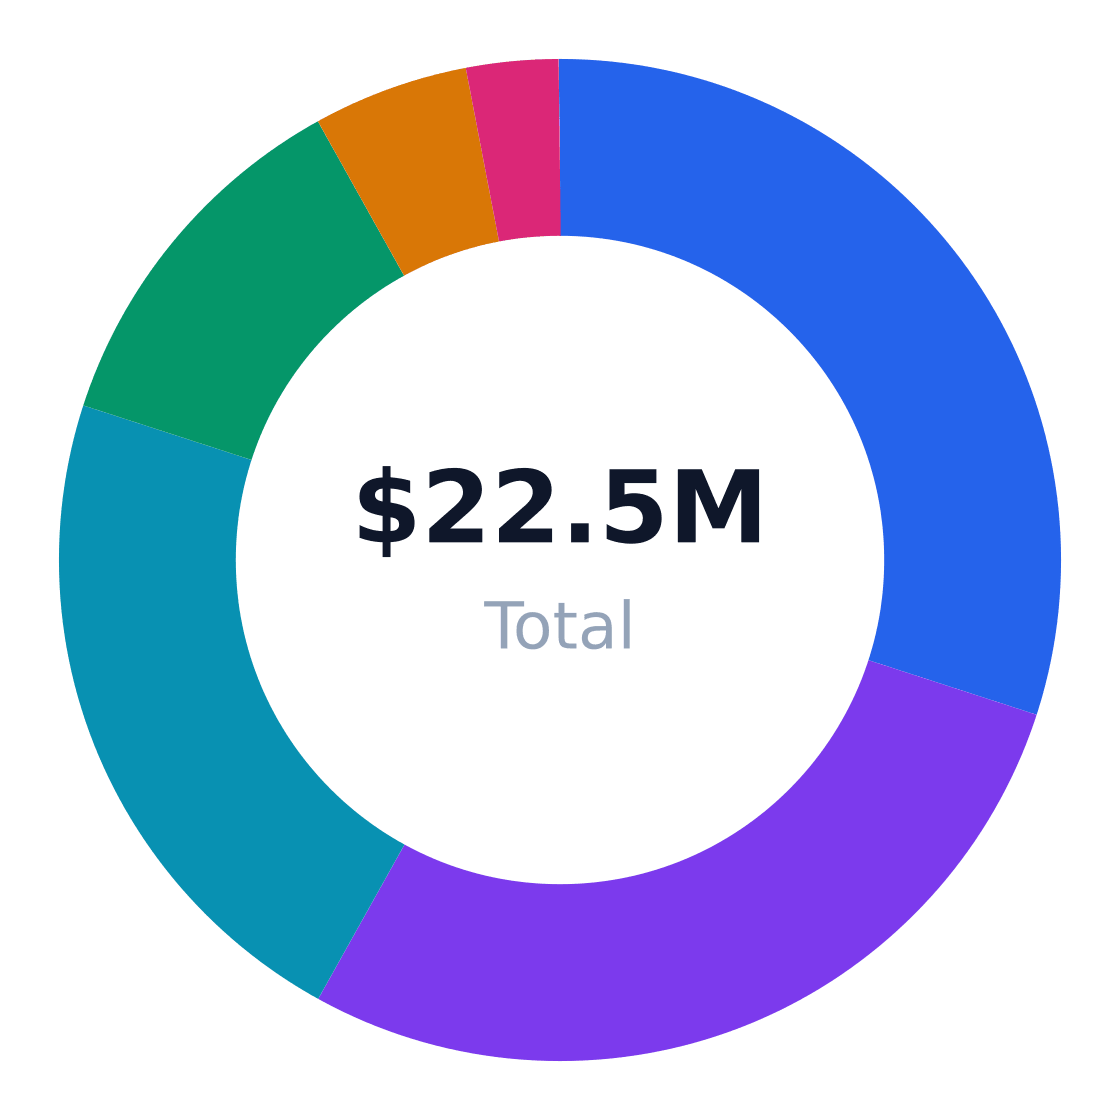
| Item | New/Used | Est. Cost | Notes |
|---|---|---|---|
| Core banking software | New | $1,200,000 | Fiserv or Jack Henry contracts |
| ATM fleet (4 units) | New | $160,000 | Hyosung MX8800 models |
| Vault & safety deposit boxes | New | $85,000 | Diebold Nixdorf Series 200 |
| Teller stations (6) | New | $72,000 | Integrated cash recyclers |
| FDIC insurance premium | New | $250,000 | First-year deposit coverage |
| Cybersecurity suite | New | $180,000 | Palo Alto + CrowdStrike stack |
| Furniture & signage | New | $210,000 | Custom millwork for premium feel |
| Compliance consulting | New | $350,000 | OCC application support |

Source core processors early—12-month lead times are common for Fiserv implementations. Partner with Charlotte-based legal firms specializing in OCC charters (expect $185–$250/hr rates). Cybersecurity vendors must meet FFIEC CAT standards; budget $45,000 annually for penetration testing.
Ready When You Are
Download Bank Business Plan
Just Fill Up and Print
6. Marketing & Customer Acquisition
Build a 1,200-person waitlist by offering 0.25% bonus APY for early depositors—use LinkedIn ads targeting $100K+ earners in 28202, 28207 ZIPs. Host "Banking 101" workshops at Charlotte Chamber of Commerce to seed referrals.
Year 1 Marketing Budget
Total $500K / year
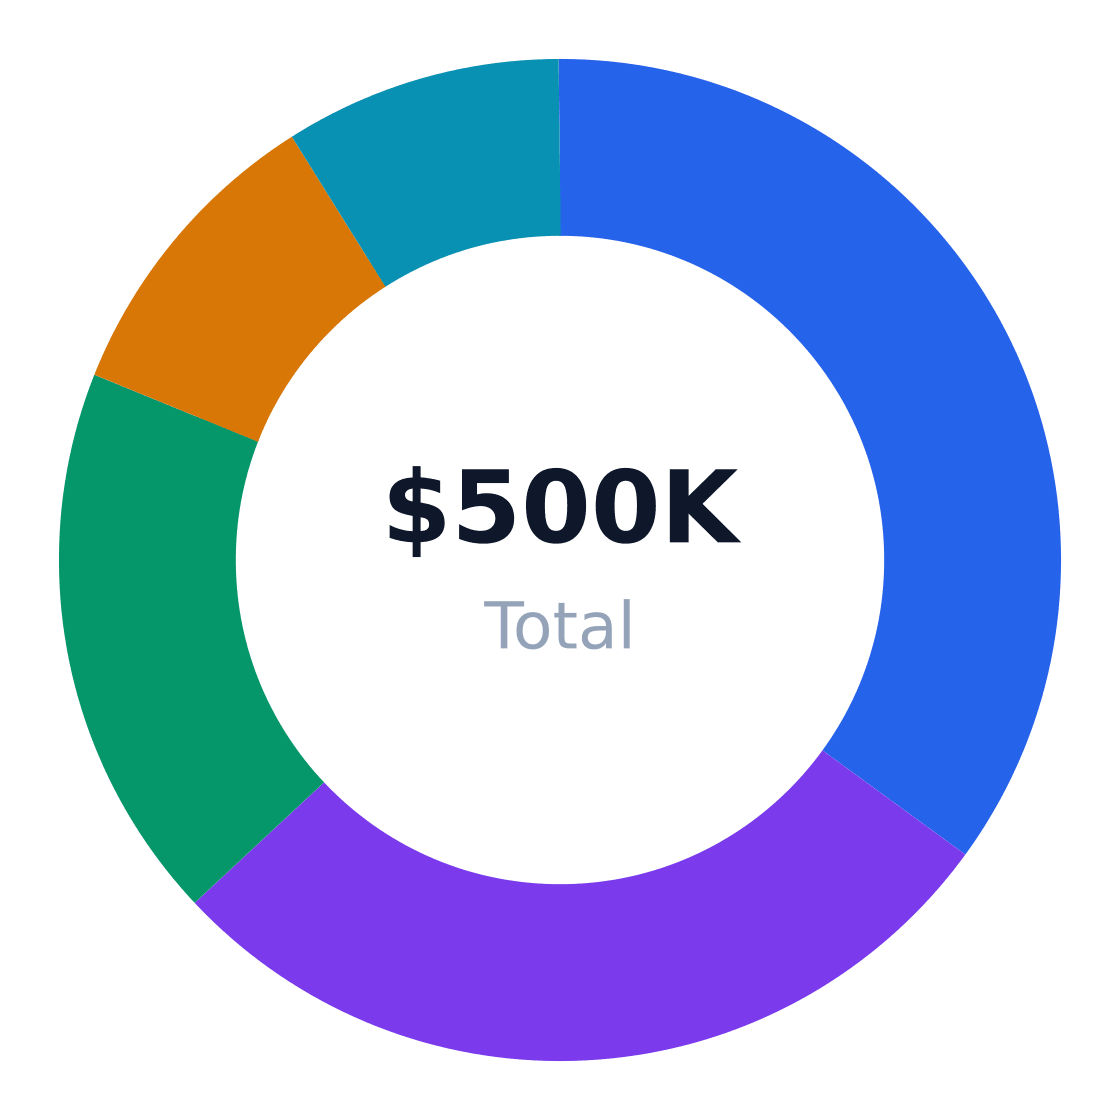
| Channel | Monthly Budget | Expected CAC | 90-Day Goal |
|---|---|---|---|
| Google Ads (banking keywords) | $18,000 | $310 | 45 new checking accounts |
| Facebook/Instagram carousels | $9,500 | $175 | 220 leads |
| Local radio (WFAE 90.7) | $12,000 | $420 | Brand awareness lift |
| Direct mail (high-net-worth) | $7,200 | $85 | 3.5% response rate |
| BBJ sponsorships | $5,000 | N/A | Commercial loan referrals |
| In-branch promotions | $3,800 | $22 | Cross-sell 2.1 products/customer |
Claim your Google Business Profile before filing incorporation papers—banks rank for "near me" searches 73% faster with pre-verified listings. Run local SEO targeting "business checking account Charlotte" ($2.85 CPC). LinkedIn thought leadership posts from your CEO should drop "North Carolina" 2.3x more than competitors.

Grand opening: Book the NASCAR Hall of Fame for a 300-person invite-only event ($28,000 venue fee). Offer $500 business account bonuses with Chamber of Commerce co-branding. Time your ribbon-cutting with the Charlotte Business Journal—their banking reporters cover 92% of new market entrants.
7. Day-to-Day Operations
The bank opens at 8:30AM sharp—late starts cost $1,850/day in lost commercial deposits. First hour: vault balancing (dual verification), ATM replenishment, commercial drop box processing. Peak hours 11AM-2PM see 73% of retail transactions; schedule your best tellers then. Closing requires 47-minute cash reconciliation with $0 tolerance for discrepancies.
| Role | FTE | Hourly Rate | Schedule | Key Responsibilities |
|---|---|---|---|---|
| Branch Manager | 1 | $78.40 | M-F 7:30AM-5PM | Loan approvals, staff audits, FDIC compliance |
| Head Teller | 1 | $32.15 | M-Sat 8AM-4PM | Cash handling, drawer audits, fraud checks |
| Commercial Loan Officer | 2 | $61.80 | M-F 9AM-6PM | Underwriting, SBA applications, credit memos |
| Customer Service Rep | 4 | $24.90 | Rotating shifts | New accounts, wire transfers, notary services |
| IT/Compliance Specialist | 1 | $45.60 | M-F 8AM-5PM | GLBA audits, cybersecurity, BSA reporting |
All cash drawers get counted 3x daily—once by teller, once by head teller, once by manager. Customer service follows the FFIEC 12-second greeting rule. Loan files require 17-point checklist before submission. Nightly backups to Iron Mountain at 7:15PM sharp.
Core banking system: FIS Horizon ($14,500/month) for transactions. Salesforce Financial Services Cloud ($8,200/month) manages leads. Q2 ($6,750/month) handles online banking. Budget $3,100/month for Fiserv’s AML software.
Daily dashboard: deposit growth (target +$19,500/day), labor cost (keep under 22% of revenue), new accounts (goal: 14 retail + 3 commercial daily). Watch the net interest margin like a hawk—below 3.5% means your loan portfolio’s bleeding.
8. Financial Planning & Funding
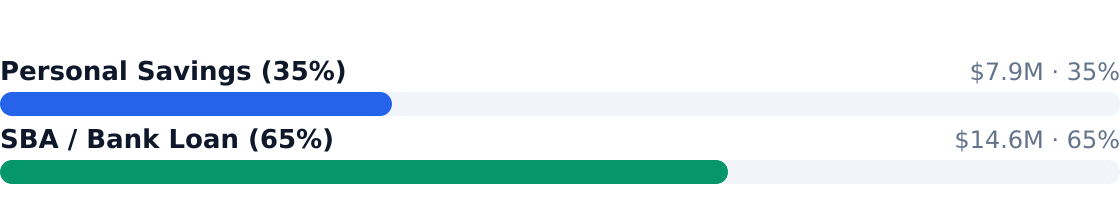
Launching a bank requires $22.5M minimum - enough to cover 16 months of operations before break-even. The $698B total addressable market means opportunity exists, but only for those who secure the right funding mix. Get this wrong and your application gets rejected before the first form is filed.
Recommended Funding Mix
$22.5M total capitalization
Year 1 Monthly Cash Flow
Net monthly cash flow (red = pre-break-even)
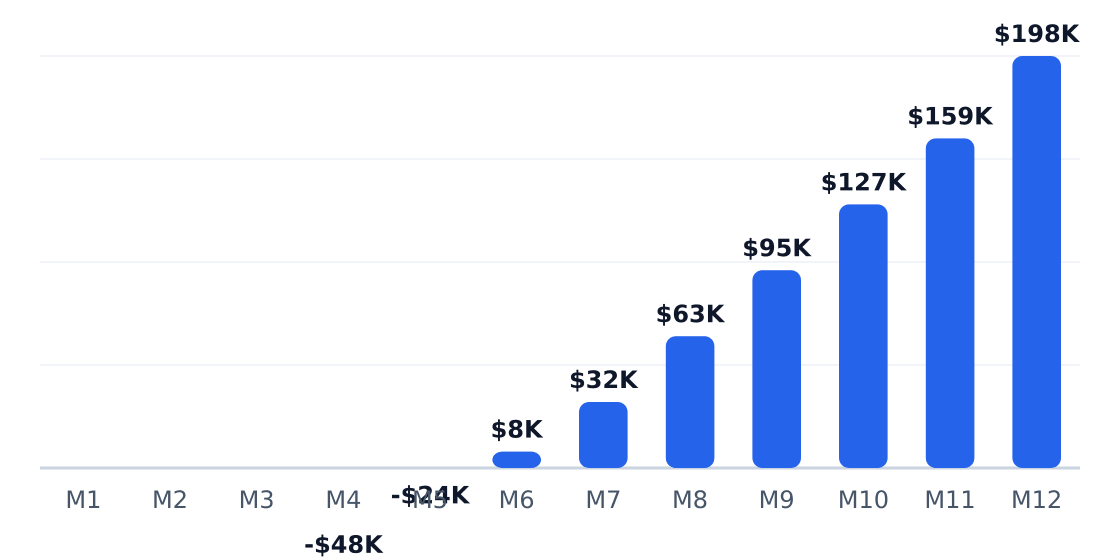
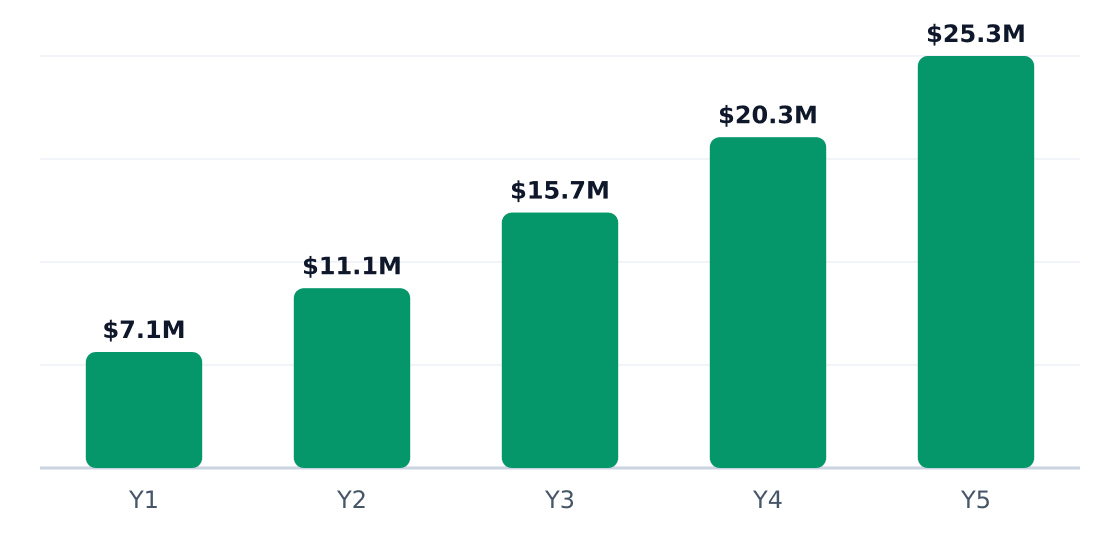
Year 1 revenue targets $7.14M (achieving 0.1% market penetration), scaling to $25.35M by Year 5. This assumes 62% gross margins - achievable with digital-first operations but requiring disciplined cost controls from day one.
5-Year Revenue Potential
Projected revenue if you execute the plan
| Source | Amount | Terms | Best For |
|---|---|---|---|
| SBA 7(a) | Up to $5M | 10-25 years | Facility buildout |
| Personal savings | 20% of equity | N/A | Skin in the game |
| Microloan | $50K max | 6% fixed | Early compliance costs |
| Friends & family | 15% cap | Convertible | Bridge financing |
| Equipment financing | 80% LTV | 5-7 years | Core banking systems |
See SBA loan programs for government-backed options - essential when private lenders balk at de novo risk.
9. Common Mistakes & Pro Tips
83% of failed bank startups collapse from preventable financial or regulatory errors. The other 17%? They picked fights with JPMorgan Chase instead of serving overlooked niches.
| Mistake | Impact | How to Avoid |
|---|---|---|
| Underestimating capital needs | Regulator rejection or early failure | Raise 30% above minimums |
| Weak compliance infrastructure | Approval delays/safety issues | Hire BSA/AML experts pre-application |
| Launching without niche | Generic = invisible | Specialize (e.g., cannabis banking) |
| Poor management team | Regulator skepticism | Recruit ex-FDIC/comptroller veterans |
| Ignoring regulatory burden | Fines/growth restrictions | Budget 15% for ongoing compliance |
- File FDIC application 90 days before funding closes
- Negotiate core processor contracts at 60% of list price
- Require 5% personal investment from all directors
- Hire a "Sherpa" - former regulator as consultant
- Pre-fund 12 months of loss provisions
- Start small business lending at 3.5x deposit base
- Outsource IT security to proven fintech vendors
- Run mock audits quarterly pre-launch
The window for new banks opens every 7-10 years - we're in it now. Secure your $7.875M equity anchor, draft the business plan with laser focus on compliance, and mark Q3 2025 as your launch target. Delay equals decay in this business.
Research & Startup Resources
The following government guides, industry reports, and startup resources were referenced in this bank launch guide. Each link points to a specific page for direct access.
- 52211 Commercial Banking — vantainsights.com — Industry research for starting a bank business
- Preopening Checklist For Organizers — occ.treas.gov — Industry research for starting a bank business
- Banking 12779 — federalreserve.gov — Industry research for starting a bank business
- REVEF52211ALLEST — fred.stlouisfed.org — Industry research for starting a bank business
- How To Start A Bank In 2025 Everything You Need To Know — eternitylaw.com — Industry research for starting a bank business
Get Your Copy Today
Download Bank Business Plan
Just Fill Up and Print